目录(6 节)

·
Building Beside Robinhood: What It Builds Itself, What It Leaves You, and 12 Numbers to Watch
For founders building beside Robinhood: what it does in-house, where it picks partners and what stays open. Five businesses worth building, three design principles, four conditional paths for the chain and twelve indicators to check every quarter.
If you are a founder, or planning a business for your company around Robinhood Chain, the first question is not “How big is the opportunity?” It is “Will the platform do it itself?”
Robinhood ships fast. At HOOD Summit on September 29 alone it announced more than a dozen products, including the AI trading agent Robinhood Agents, Agent Apps, U.S. perpetual futures, earnings contracts, the full launch of the social trading community Robinhood Social, and plans for weekend stock trading. It is moving into many spots that used to belong to third parties.
The Framework: The Platform Boundary
Judging by the products Robinhood has shipped and the way it partners, onchain business positions fall into three groups:
| Group | Positions | Robinhood’s approach |
|---|---|---|
| In-house | Stock Token issuance, the main wallet, the Earn frontend, AI trading agents, social trading, prediction markets, U.S. perpetuals | Builds them and places them in its own interfaces |
| Selected partners | Lending protocols, vault curation, public DEX liquidity, perpetuals, oracles, custody, compliance analytics | Does not build; embeds a few chosen partners |
| Open space | Launchpads, trading terminals, data tools, games, bridges, compliance middleware, tax, institutional back office | Neither builds nor selects; anyone can enter |
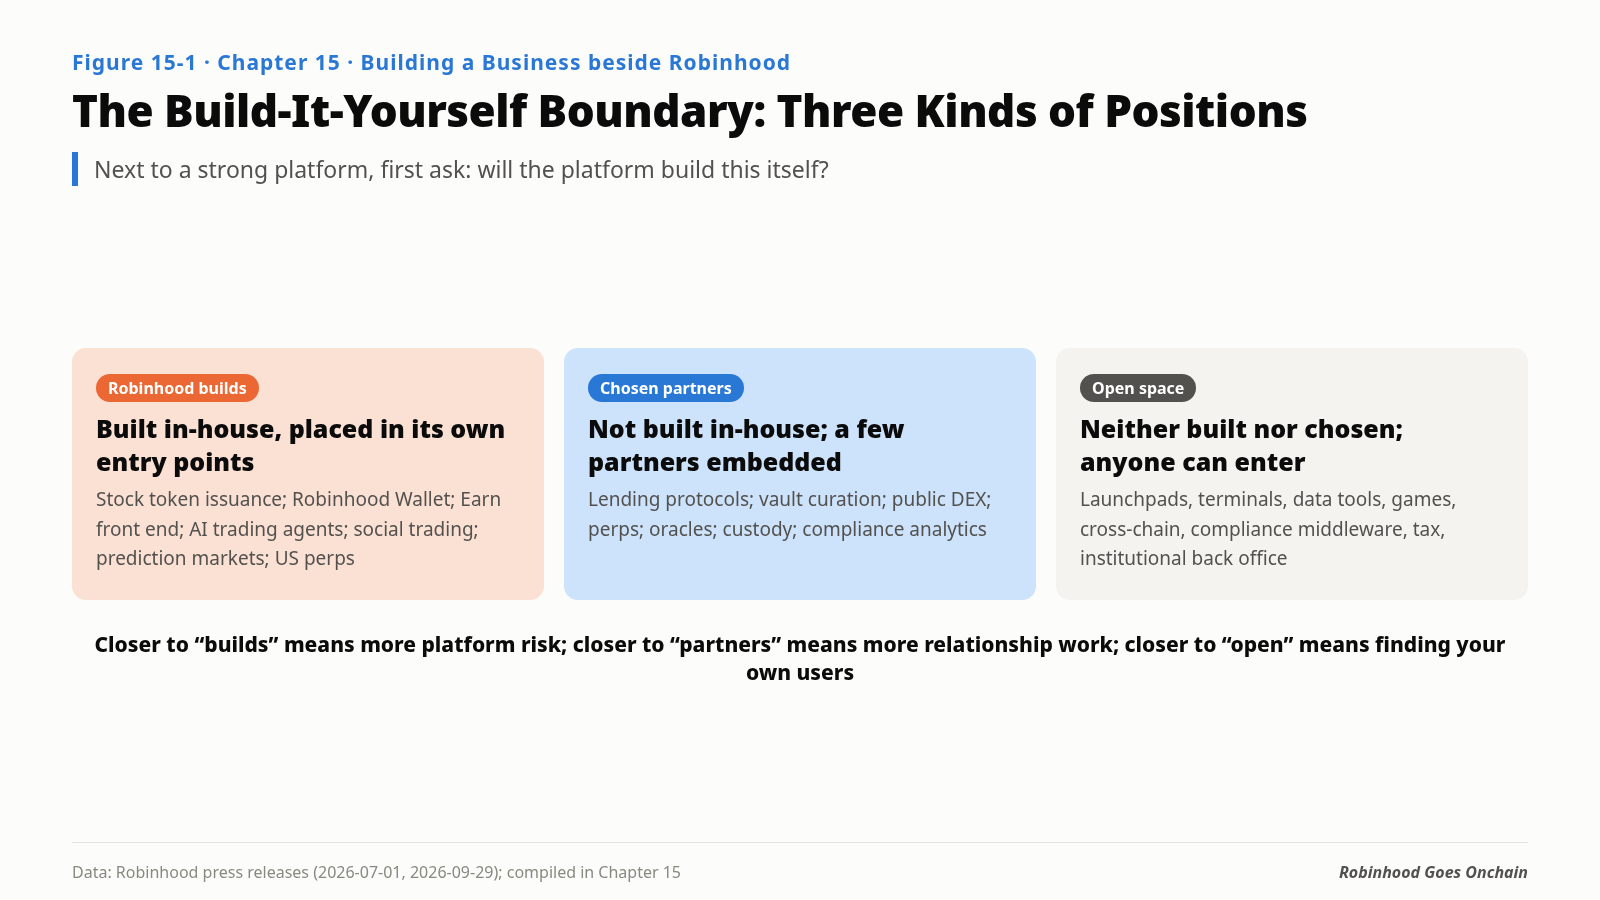
The closer you sit to in-house, the higher the platform risk. The closer to selected partners, the more you depend on your relationship with Robinhood. The closer to open space, the more you have to find your own users.
Five Businesses Worth Building
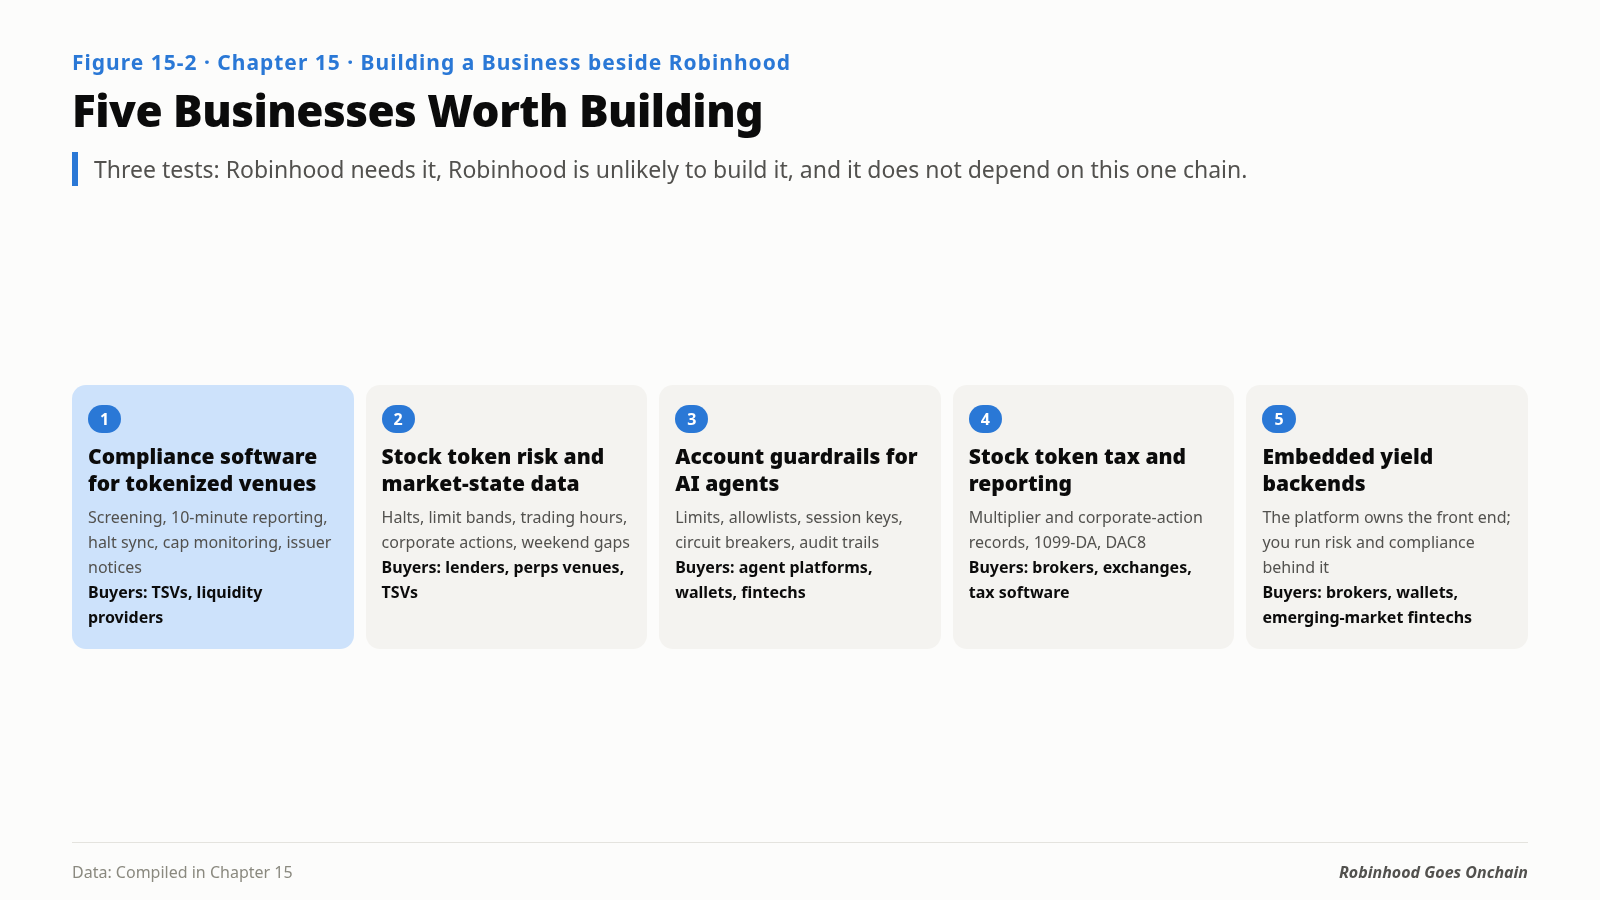
These five meet three conditions at once: Robinhood needs them, Robinhood is unlikely to build them all, and they are not tied to this one chain.
- Compliance software for tokenized-securities venues. The SEC’s innovation exemption requires every venue to screen participants and sanctions, report trades within 10 minutes, halt in sync with the underlying stock, monitor ticker and volume caps, notify issuers and run a 30-day objection process. Before September 17 these requirements had no buyers; afterward every venue has to build or buy them. The regulation is itself a requirements list.
- Risk and market-state data for stock tokens. Once stock tokens enter lending and perpetuals, protocols need more than a price: is the stock halted, has limit-up/limit-down triggered, is the market in session, was there a dividend or split, did the multiplier change? Price gaps when U.S. markets are closed, especially over weekends, are the biggest risk in using stock tokens as collateral.
- Account guardrails for AI agents. Autonomous agents need spending limits, asset allowlists, session keys, circuit breakers and audit trails. Robinhood’s own agent trading requires a separate account the user funds deliberately, starts with stocks only, and allows no leverage. That kind of staged delegation is a capability every onchain agent account needs.
- Tax and reporting for stock tokens. With a multiplier, the onchain balance stays fixed while the economic interest per token changes, so tax systems must record multipliers and corporate actions together. Cost basis and income recognition depend on the jurisdiction and the specific event. The U.S. 1099-DA and the EU’s DAC8 each have their own scope, and holders in 120-plus countries face different rules.
- Embedded yield backends. Earn proved the model: the protocol is the backend, the platform owns the frontend. Plenty of brokers, wallets and emerging-market fintechs want to offer onchain yield without building risk and compliance themselves.
Three Design Principles
- Be portable across chains. One stock already exists as six tokens on five chains. Launch on Robinhood Chain; do not treat it as the only one.
- Build middleware, not a frontend. Wallets, trading apps, social and agents are where Robinhood is going in-house; compliance, risk, data, accounting and market making are where it needs partners.
- Write platform rule changes into the product. Ordering, transaction filtering, freeze powers and Wallet’s default routing can all change. Your product should degrade gracefully.
Four Paths
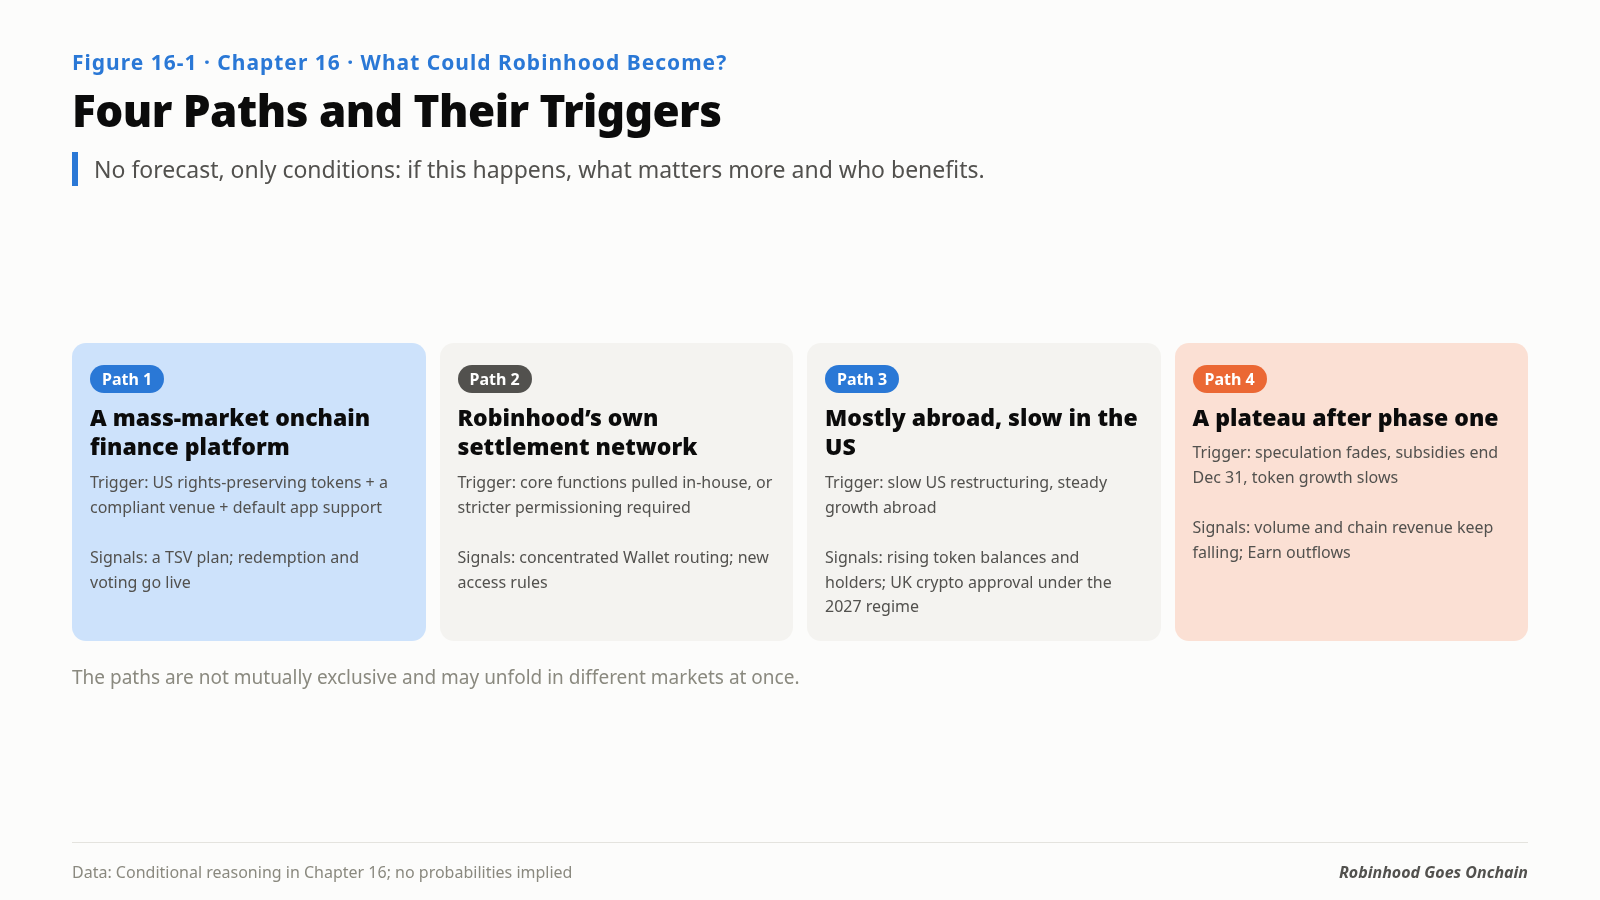
What happens to this chain next depends not on first-phase excitement but on things that have not happened yet. So no prediction here, only conditions:
| Path | Trigger | Early signals | Capabilities that matter most |
|---|---|---|---|
| 1. A mass-market onchain financial platform | Rights-preserving tokenized stocks in the U.S., with a compliant venue Robinhood sets up or affiliates with | A U.S. Stock Token or venue plan; in-kind redemption and voting go live | Issuer relationships, compliance middleware, risk data, institutional custody |
| 2. Robinhood’s own settlement network | Core functions pulled in-house, or regulators demand tighter permission controls | Wallet routing concentrates; new access requirements | Being one of the few selected partners |
| 3. Growth abroad, slow progress in the U.S. | U.S. restructuring is slow while Stock Tokens keep growing offshore | Holders keep rising with no U.S. announcement | Emerging-market fiat rails, local tax, long-tail market making |
| 4. A plateau | Speculation keeps fading and subsidies end after December 31 | Volume and chain revenue keep falling after subsidies; Earn deposits leave | Portability across chains, no dependence on one chain’s traffic |
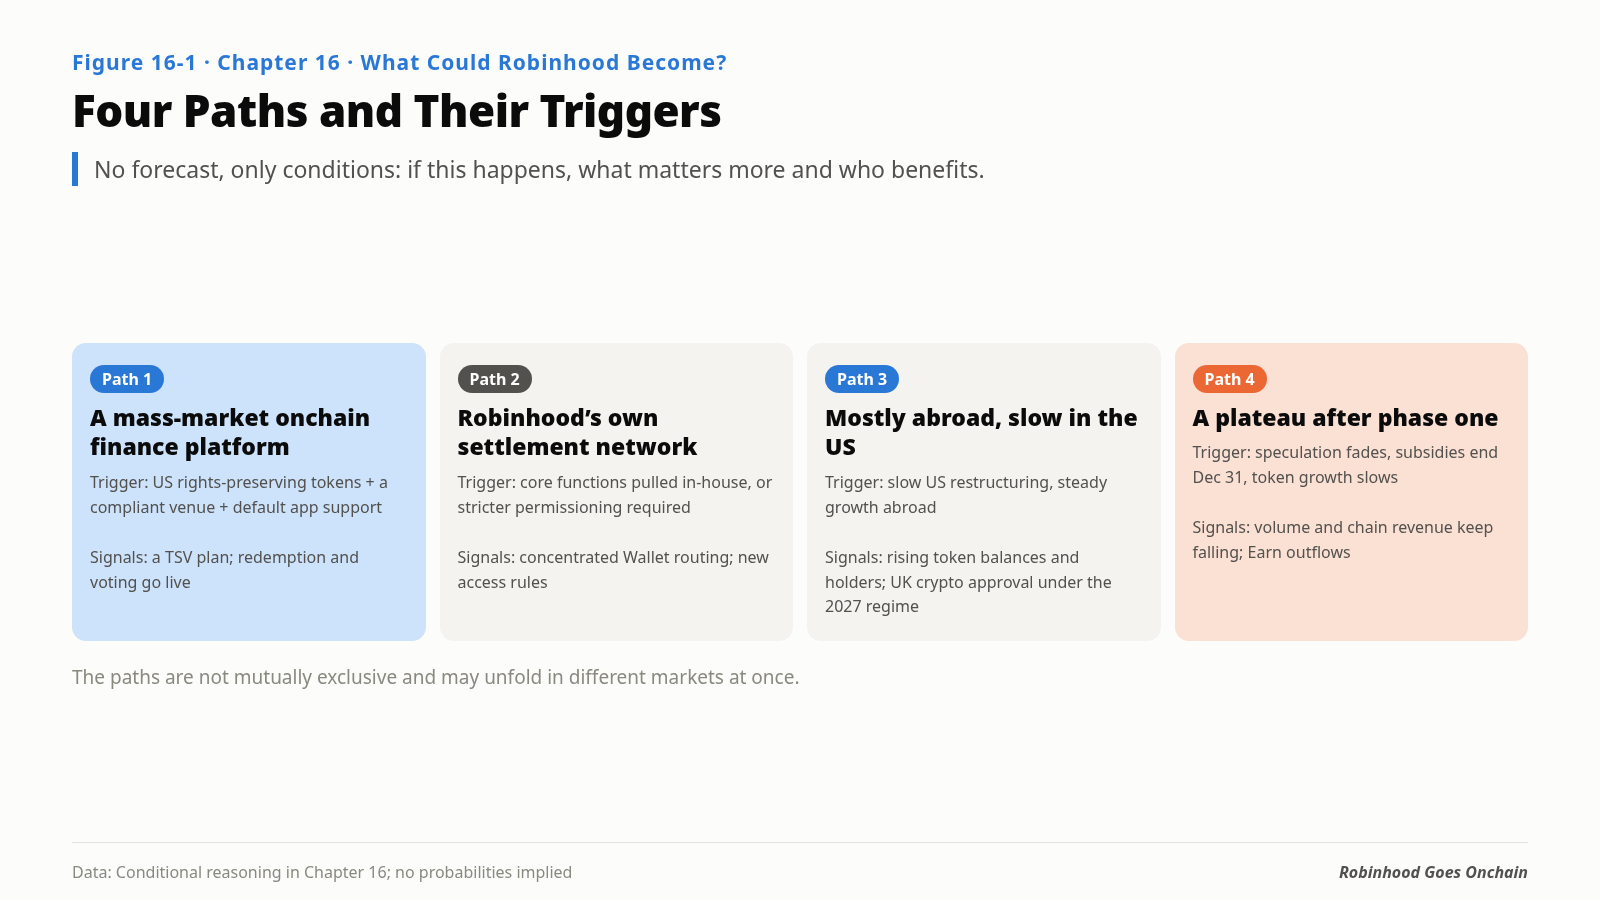
The paths are not mutually exclusive. The most likely outcome is several at once in different markets: growth abroad, say, while Robinhood slowly prepares Path 1 in the U.S.
Twelve Indicators to Check Every Quarter
| # | Indicator | October 2026 reading |
|---|---|---|
| 1 | Average daily DEX volume (30-day) | About $1.3B a day, Sep. 15–Oct. 14 |
| 2 | Chain-level revenue | About $50,000 a day on average, Oct. 1–13 |
| 3 | App users’ share of onchain trades | About 1–2% (CoinDesk Research estimate, subject to identification limits) |
| 4 | Earn / Morpho deposits | About $580M (Oct. 1) |
| 5 | Stock Token holders and cumulative volume | About 200,000 holders, about $15B (Oct. 12) |
| 6 | Number of Stock Tokens | About 200 |
| 7 | In-kind redemption and voting | Promised, no date |
| 8 | U.S. venue or rights-preserving tokens | No public plan |
| 9 | L2BEAT stage and upgrade time locks | Not yet Stage 0 |
| 10 | Ordering rules | First come, first served; paid priority under review |
| 11 | Wallet default routes and new integrations | Lighter, Arcus, Uniswap |
| 12 | Chain disclosure in financial reports | Not reported separately; Q3 results due Oct. 27 |
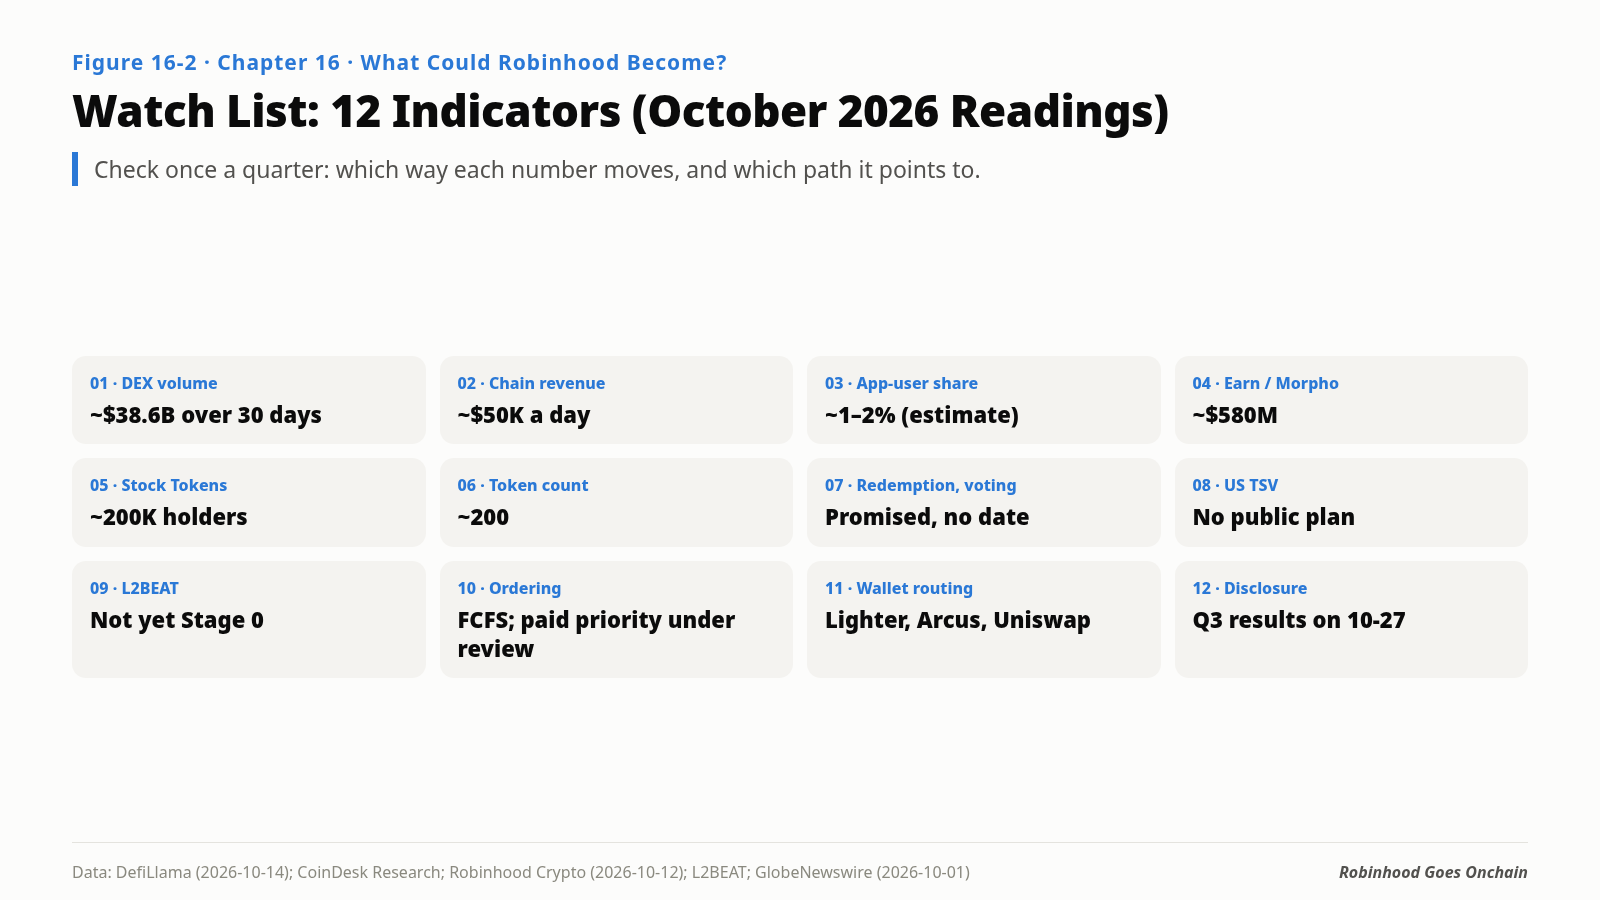
The bear case belongs on the list too. The distribution switch may stay only partly open for a long time, because pushing customers into self-custody weakens Robinhood’s own monetization. The offshore structure has a ceiling. Base has roughly six times this chain’s TVL and five times its stablecoins. These are not conclusions; they are questions to check each quarter.
The Takeaway
Anyone can copy the chain. No one can copy the customers, but the customers will not move onchain by themselves either. What Robinhood alone has is more than 28 million customers who have opened accounts, passed KYC and trust the brand, plus a front door that can put products in front of them. In year one, Earn opened the deposit switch; the trading switch stayed shut.
For Robinhood, distribution is power. When it chooses to use that power will define the chain’s second year.
Of the 12 indicators, which one would you track every quarter?
— Adapted from Robinhood Goes Onchain: A Broker’s First Year, Chapter 15, “Building a Business beside Robinhood,” and Chapter 16, “What Could Robinhood Become?”
The full book (17 chapters, 48 figures, first 3 chapters free to read): https://pickful.ai/books/qx7q
转发此帖子?
与您的关注者分享。
回复