Contents (5)

·
In Robinhood Chain's Busiest Month, the Chain Operator Ranked Behind Apps and DEXs
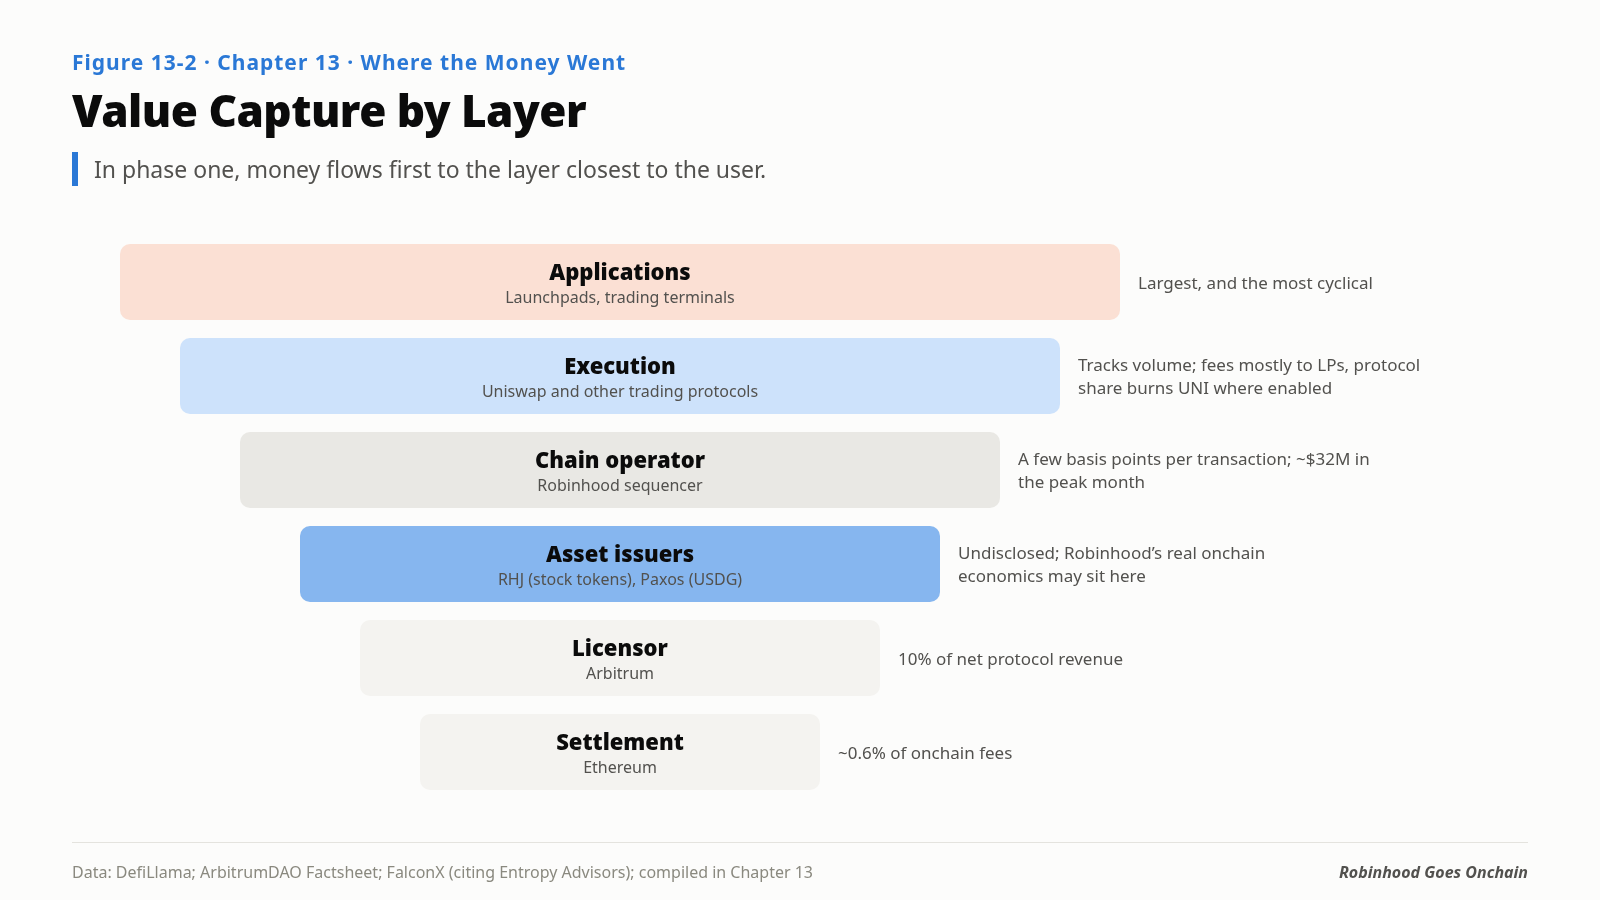
In September 2026, launchpads, DEXs and trading terminals each took more fees on Robinhood Chain than the chain operator did. The value-capture stack shows money reaching the layers closest to users first, and why Robinhood's real onchain economics sit at the asset and distribution layers.
If you are evaluating an investment tied to Robinhood Chain, whether HOOD, a protocol token or a startup, answer one basic question first: where does the money made onchain end up?
Buy a new token or a stock token on this chain and the trade may pass through a wallet or trading terminal, an aggregator, a DEX, a launchpad, the chain’s sequencer, Ethereum data posting and Arbitrum’s licensing share. Each layer can take a fee.
Sort September 2026, the busiest month so far, by layer (DefiLlama’s 30-day protocol fee measures):
| Layer | September fees | Main participants |
|---|---|---|
| Launchpads | About $143M | Pons, NOXA, o1 and others; much of it paid to token creators |
| Execution protocols | About $148M | Uniswap, Fables, Ramses and others; much of it paid to liquidity providers |
| Trading terminals | About $51M | GMGN, fomo, Axiom |
| Chain operator | About $35.93M (about $32.31M after Ethereum data costs) | Robinhood, which then pays 10% to Arbitrum |
| Lending and perpetuals | About $3.4M | Lighter, Morpho |
Two caveats. First, one trade can be charged at the frontend, the launchpad and the underlying DEX, so the layers must not be added up as a deduplicated economic cost for the chain. Second, the chain-operator row uses DefiLlama’s chain-level method; it is not revenue recognized in Robinhood’s financial statements, which do not report it separately.
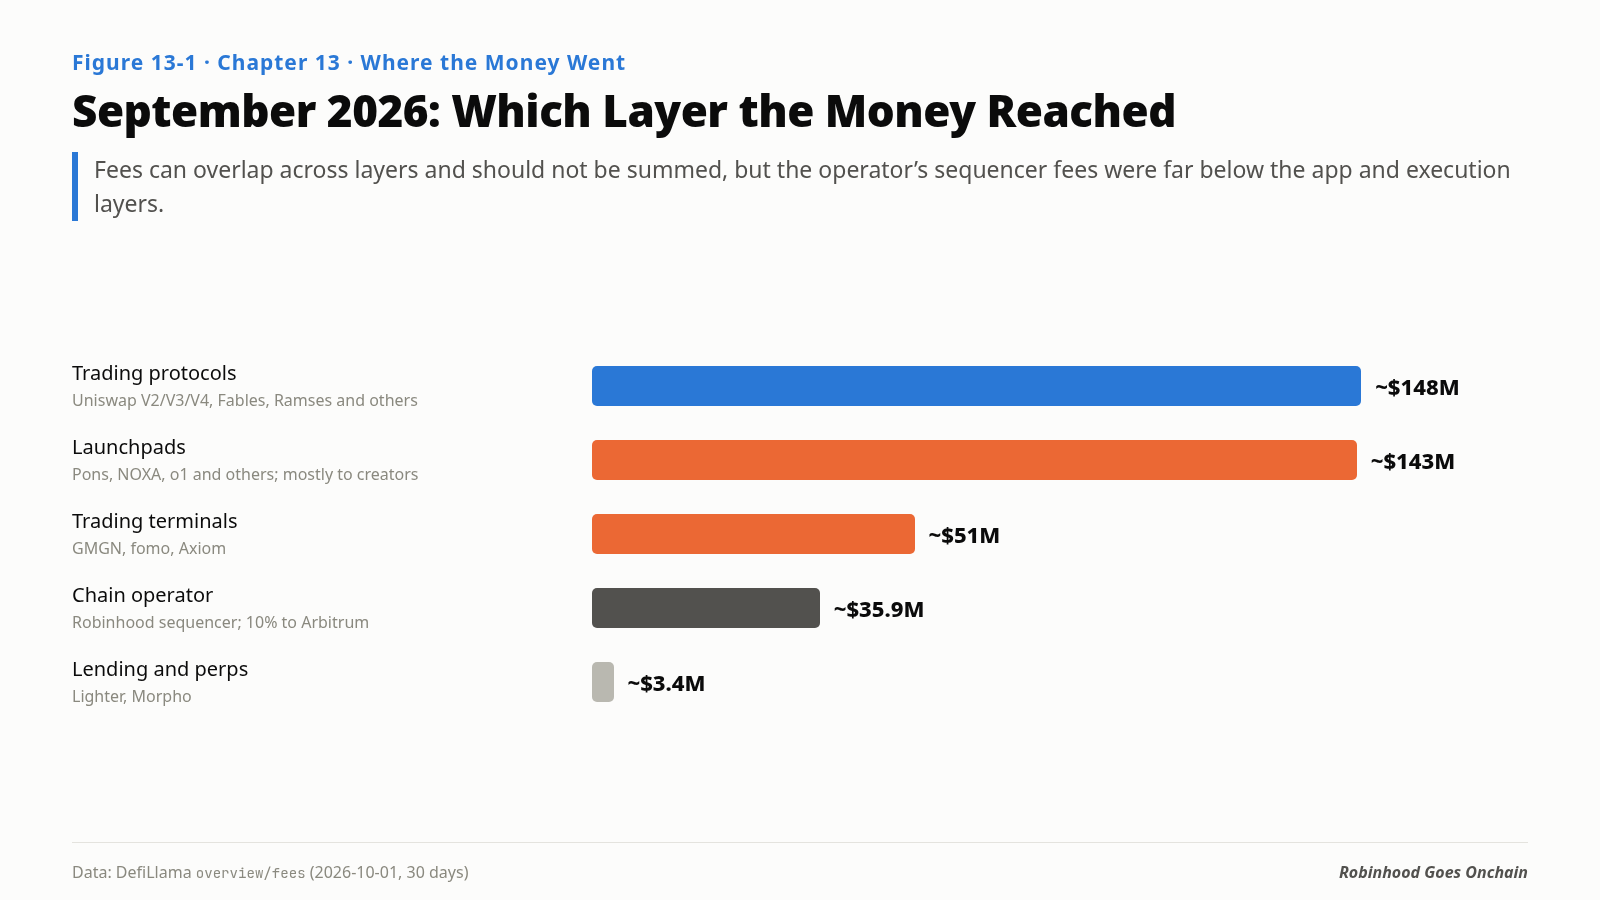
Even so, the ranking is clear: the chain operator comes in behind both the application layer and the execution layer.
The Framework: The Value-Capture Stack
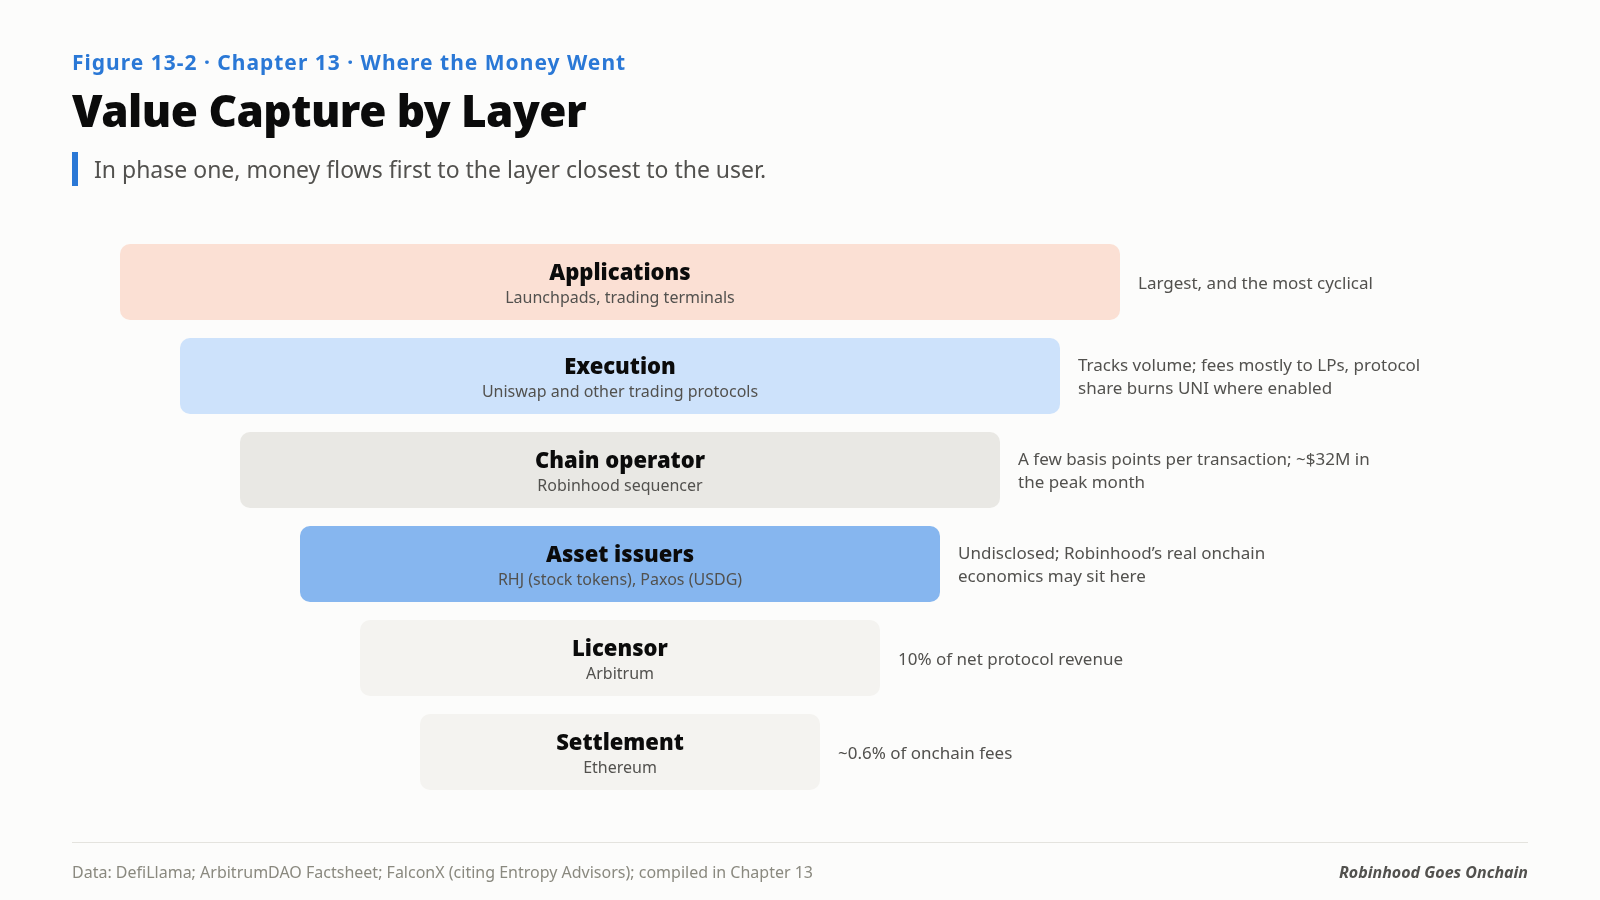
In a new chain’s first phase, money reaches the application and execution layers closest to users first, and only then the chain operator, the technology licensor and the settlement layer.
| Layer | How it earns | First-phase reading | What makes it bigger |
|---|---|---|---|
| Applications (launchpads, terminals) | Launch fees, trading cuts | Largest, most cyclical | New uses, such as AI agents issuing tokens |
| Execution (Uniswap and others) | Trading fees, mostly to LPs; protocol share where switched on | Large, follows volume | Stock tokens and stablecoins become the main source of volume |
| Chain operator (Robinhood) | Sequencing fees, a few basis points per transaction | Medium, about $32M in the peak month | More transactions; paid priority ordering |
| Asset issuers (RHJ, Paxos) | Creation and redemption spreads; stablecoin reserve income | Undisclosed | Growth in Stock Token balances and USDG |
| Licensor (Arbitrum) | 10% of net protocol revenue | Small | Growth in chain revenue |
| Settlement (Ethereum) | Data-posting costs | Very small, about 0.6% of chain fees | More onchain data |
Two implications.
Robinhood’s income at the chain layer is thin by design. In the CFO’s words, it charges a few basis points per transaction, not on volume.
Robinhood’s real onchain economics sit at the asset layer, not the chain layer. Stock Token issuance and redemption, a share of USDG reserve economics (Robinhood is one of the initial members of the Global Dollar Network), services inside Wallet, and the indirect value of keeping customers in its own ecosystem: none of it shows up in sequencer revenue. These numbers are not public yet, and they are what to read for in Q3 and later reports.
Traffic Has to Be Chosen
Which layer the money flows to depends heavily on where Robinhood’s entry points send traffic.
Anyone can deploy on the chain, but Robinhood has only one front door. The Morpho alliance was embedded in the app and got Earn’s deposits. Lighter, Arcus and Uniswap were embedded in Wallet and got trade routing. Uniswap, officially positioned as the main source of public liquidity, handles about 77% of the chain’s volume, and the chain at one point supplied more than half of Uniswap’s volume across all chains.
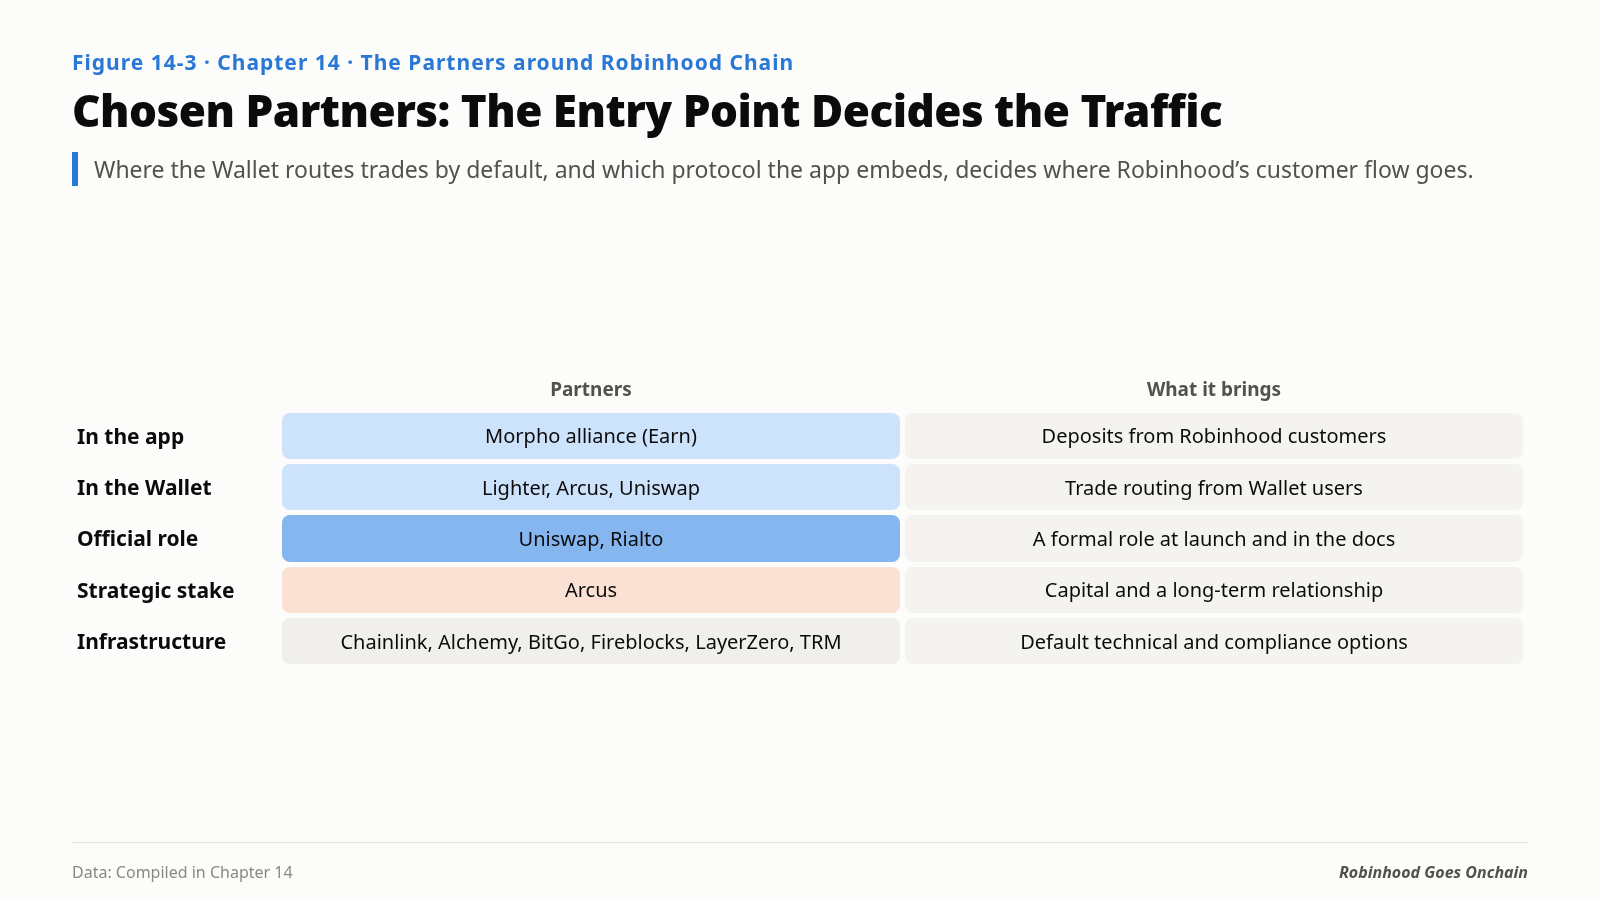
Deployment needs no permission; traffic has to be chosen. Where Wallet routes trades by default, and which protocol the app embeds, decides which layer Robinhood customers’ money reaches.
After the First Phase
October’s data shows the trading layer pulling back. Chain-wide daily protocol fees fell from over $10 million on some mid-September days to about $2–5 million a day. Daily chain-level revenue averaged about $50,000 from October 1 to 13. Daily DEX volume dropped from about $3.67 billion on September 4 to around $1 billion.
The deposit layer held roughly flat: TVL went from about $1.04 billion on October 1 to about $1.05 billion on October 14, and stablecoins from about $1.04 billion to about $1.07 billion.
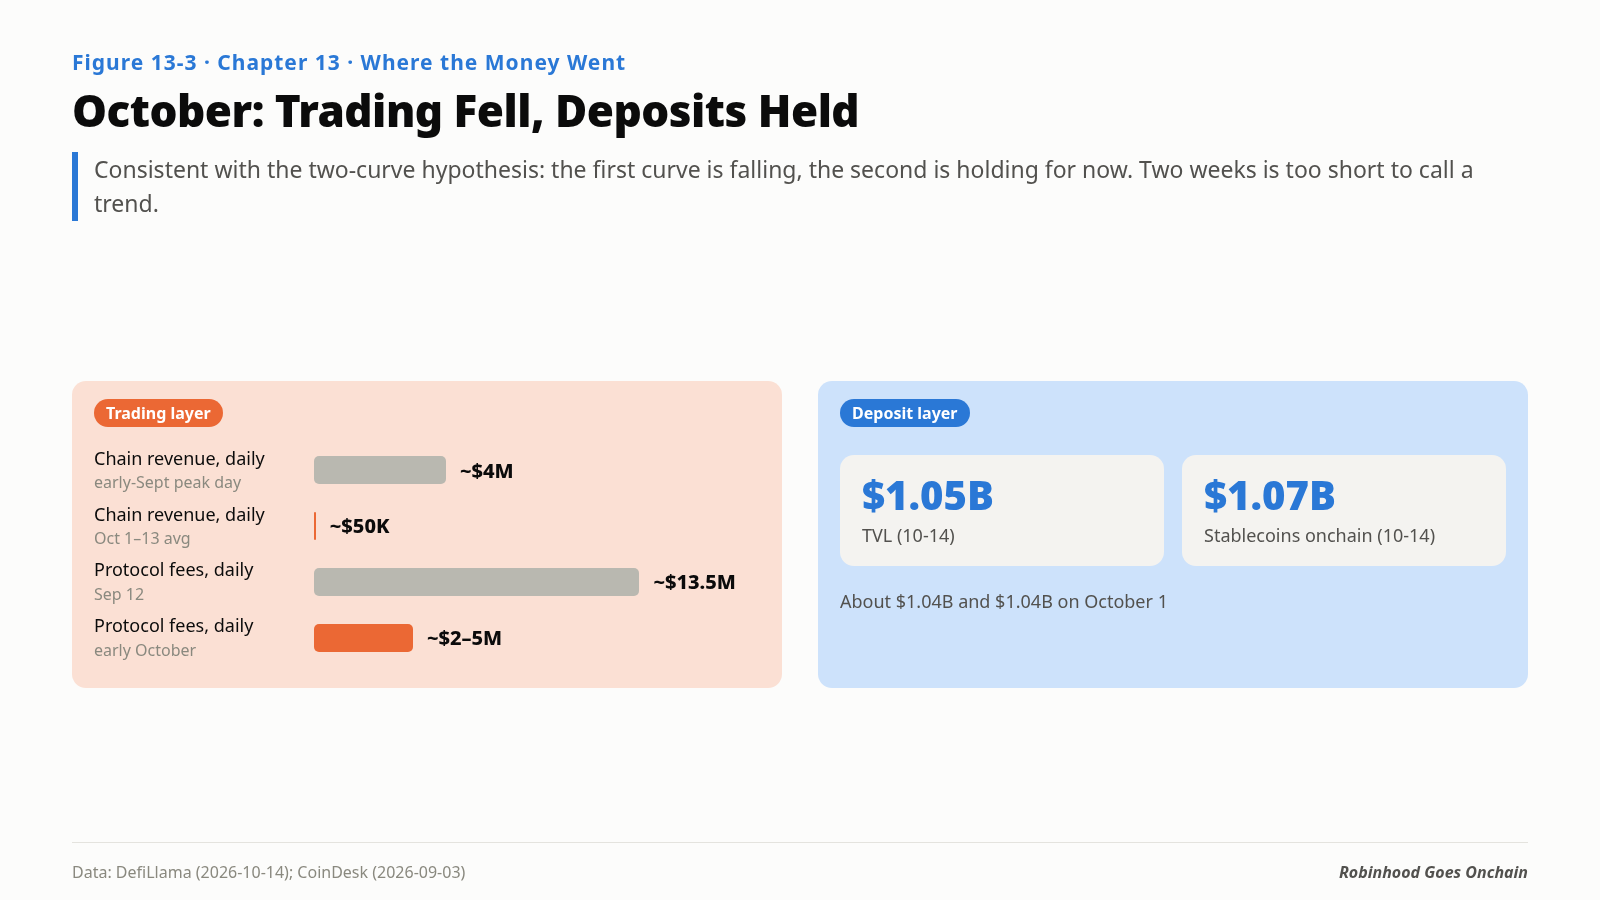
That fits the hypothesis that the trading layer falls back while capital stays. But it is a two-week snapshot from early October, and Earn subsidies and a few concentrated vaults may shape it. It is evidence for the hypothesis, not confirmation of a trend.
Different Investments, Different Layers
| Investment | Layer you are betting on | Main variables |
|---|---|---|
| HOOD | Distribution + assets + chain operation, heavily diluted by the rest of the company | Whether distribution switches open; whether U.S. tokenization lands |
| UNI | Execution | Whether this chain’s volume lasts; protocol-fee implementation |
| Launchpad tokens | Applications | Issuance and trading cycles; cross-chain expansion |
| ARB | Licensor | DAO treasury income, not distributed to holders |
| ETH | Settlement + gas asset | Weak transmission |
| Lending tokens | Deposits | Deposit retention after subsidies; stock-token collateral markets |
This is not a price view on any asset. The table only helps you ask, before you judge: which layer am I betting on, and where does that layer’s money come from?
The Takeaway
Onchain money reaches the layer closest to the user first. At the chain layer, Robinhood collects a toll; the real accounts are in assets and distribution. When stock tokens, lending and AI agents become the main uses, the money will be redistributed again.
The project you’re watching right now: which layer is it betting on?
— Adapted from Robinhood Goes Onchain: A Broker’s First Year, Chapter 13, “Where the Money Went,” and Chapter 14, “The Partners around Robinhood Chain”
The full book (17 chapters, 48 figures, first 3 chapters free to read): https://pickful.ai/books/qx7q
Repost this post?
Share with your followers.
Reply