Contents (5)

·
Wrapping Isn't Sourcing: Binance took $557M for SpaceX shares it never delivered
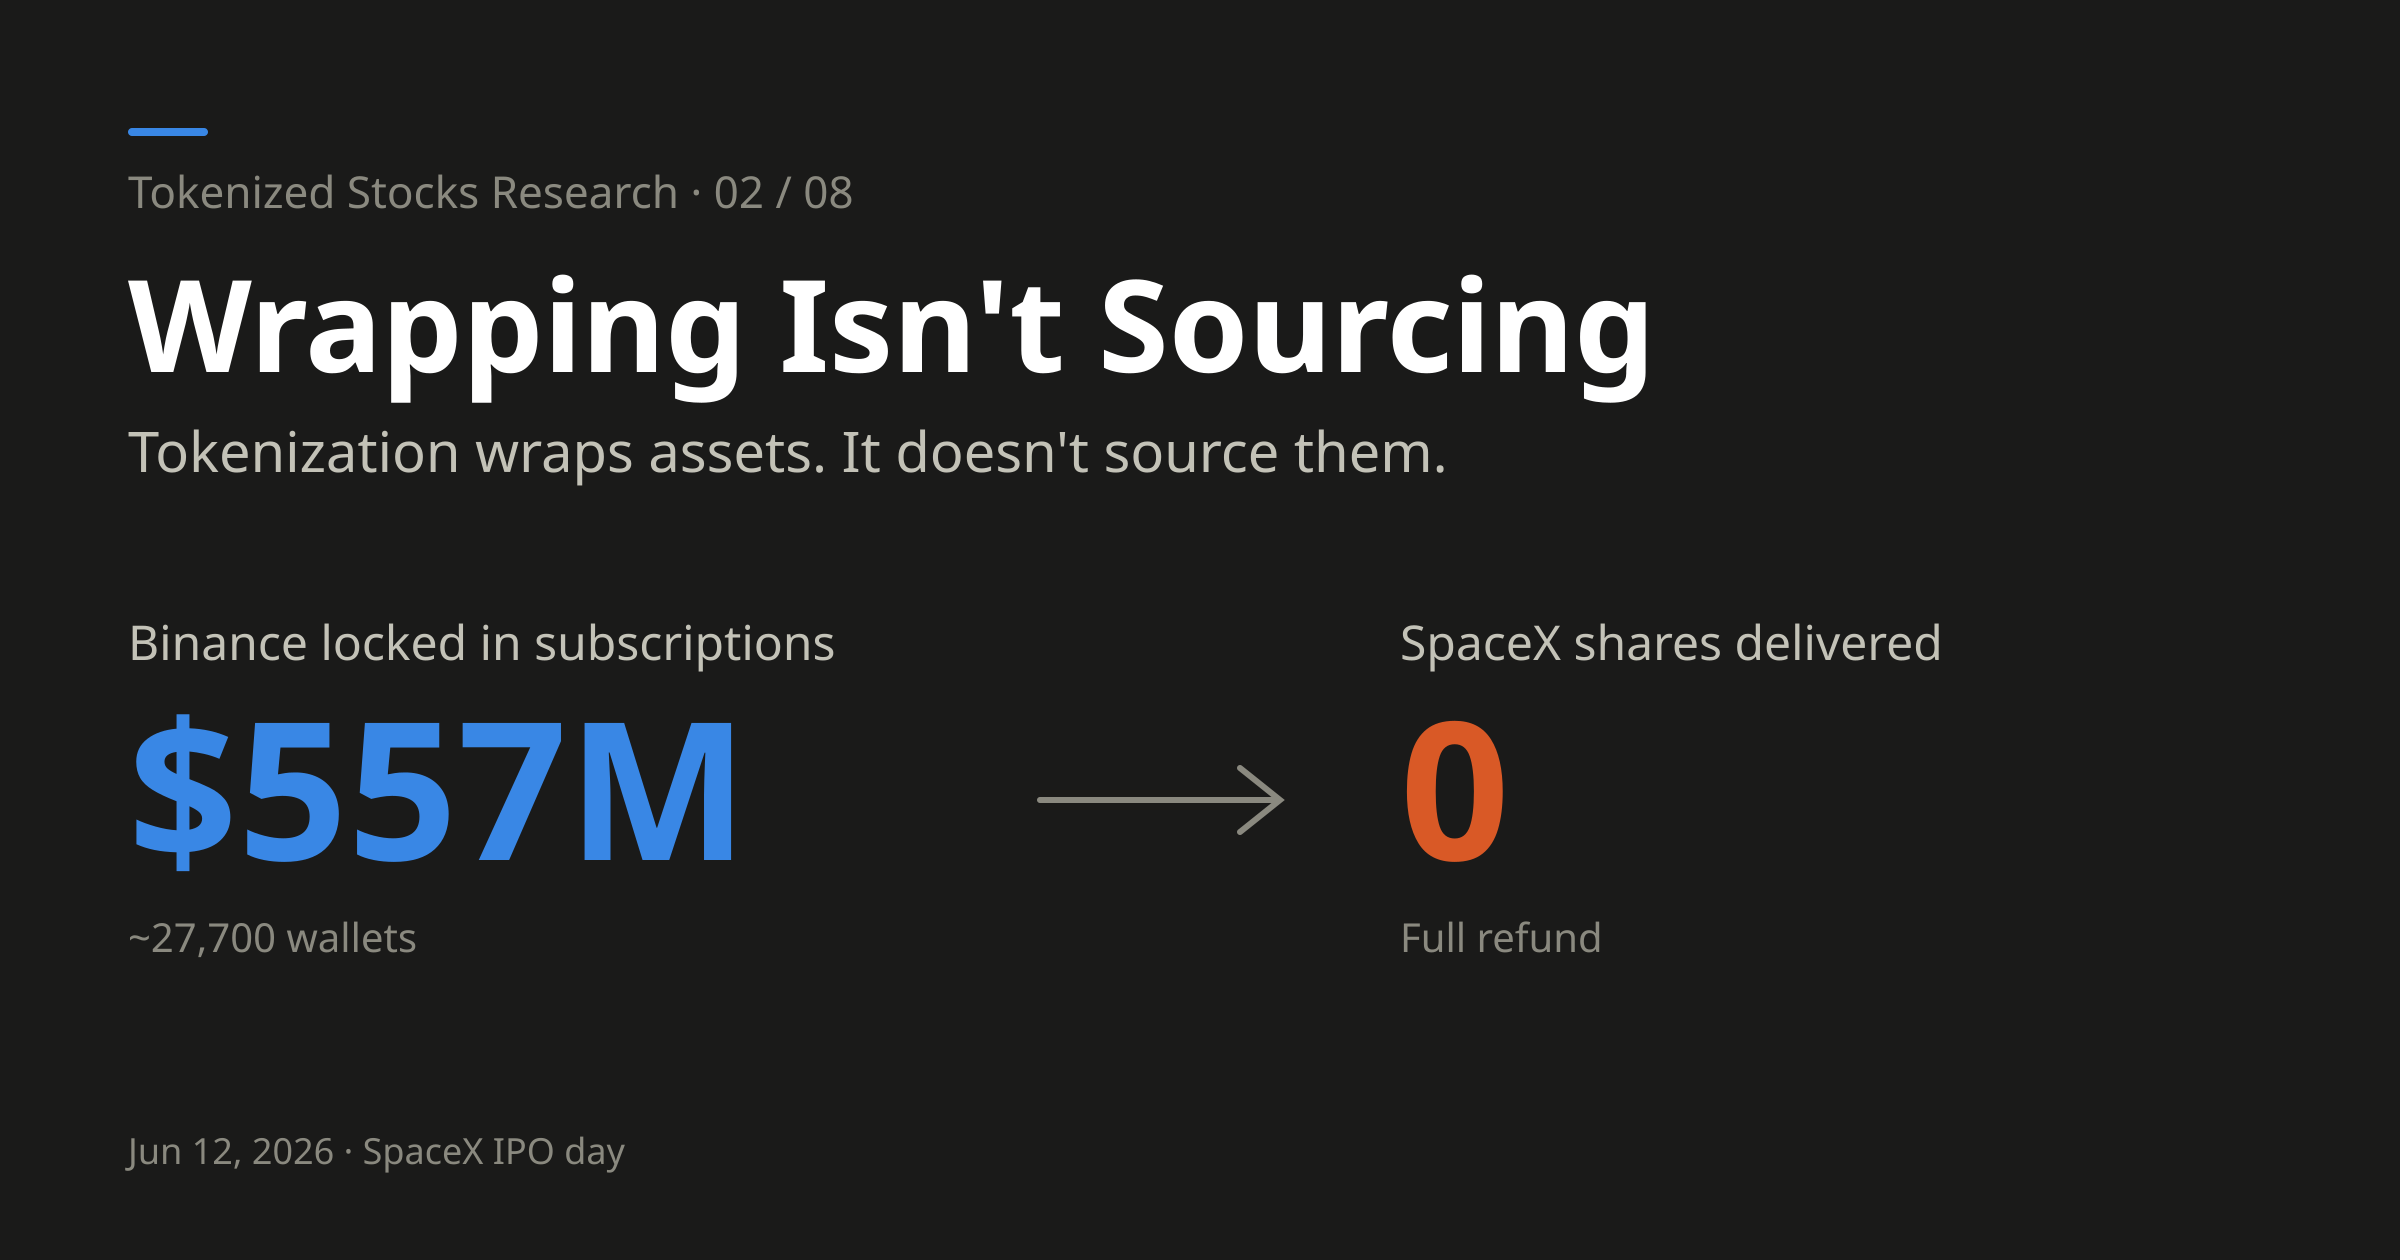
On SpaceX's IPO day, Binance locked $557M in tokenized subscriptions and refunded all of it without delivering a single share. Tokenization wraps assets; it doesn't source them. When the underlying is scarce, that difference is everything.
If you’re building a tokenized issuance product, or you believe “onchain can route around traditional finance,” this is a full autopsy.
On June 12, 2026, SpaceX listed on Nasdaq. Priced at $135, opened at $150, closed at $161.11, market cap above $2 trillion. Oversubscribed more than 4x.
The same day, Binance Wallet, Bybit, Bitget Wallet and MEXC all cancelled their tokenized SpaceX subscriptions and refunded everyone.
Binance alone had locked about $557M in USDC from roughly 27,700 wallets.
All four gave nearly the same explanation: their upstream supplier, xStocks, couldn’t get enough of the underlying shares. Kraken’s own users got about 4.3 SPCXx each.
Wrapping isn’t sourcing
This is the one framework to take from the whole episode.
Tokenization does wrapping: it takes an asset that already exists and puts it in a new legal and technical shell, so it can move 24/7, be self-custodied, and plug into DeFi.
Tokenization does not do sourcing: it creates no new supply of shares, and it doesn’t put you on the underwriting syndicate’s allocation list.
When the underlying is plentiful, the difference doesn’t matter. When the underlying is scarce, the difference is everything.
IPO allocation is a scarce resource handed out through relationships. xStocks had to go through the same allocation pipeline as Fidelity and Schwab to ask for shares, and it got a sliver.
Demand was never the problem. Demand was 4x oversubscribed, and that was exactly the problem.
The refunds show where the chain of responsibility breaks
Put the four platforms’ responses side by side:
| Platform | Compensation |
|---|---|
| Bybit | Full refund + 4 days of 10% annualized |
| MEXC | Full refund + 2-day 6% APY boost coupon + $500 SPCXUSDT trial credit |
| Bitget Wallet | Full refund + 5% fee rebate + $10 gas voucher + whitelist for future tokenized IPOs |
| Binance | Full refund + ~$1M SPCXB airdrop (about $35 per user) |
All handled decently. But notice what’s missing.
None of the four downstream distributors showed users any delivery guarantee from upstream, or any recourse against it.
They took users’ money and in the end could only say “circumstances outside of our control” (Binance’s words). And Kraken wasn’t a victim here. It owns xStocks. It was the link that broke.
That’s the structural flaw in the wrapping business: every extra layer of wrapping adds another point of delivery dependency, and the end user usually can’t make a claim against it directly. Yet the user sees the same logo.
A throwaway comment became regulation three months later
On the day, Bullish CEO Tom Farley posted on X:
“Maybe tokens should be approved by the issuer and therefore be the real underlying shares. Just a thought.”
Three months later, on September 17, 2026, the SEC’s innovation exemption (Release 34-106402) turned that thought into two hard conditions:
- Token holders must have the same rights as holders of traditional shares, including dividends and voting.
- Listed companies can object to their shares being tokenized; platforms must give written notice and wait 30 days.
Synthetic exposure products are explicitly excluded.
In other words, most tokenized stock products by trading volume today (xStocks, Ondo Stocks, bStocks, Robinhood Stock Tokens) don’t structurally qualify for this exemption.
Galaxy Research said it most plainly: Robinhood’s Stock Tokens can’t qualify under any reading, because its own prospectus describes them as debt securities that “do not grant any underlying legal or beneficial rights.”
If you’re building this
Three checks you can act on:
-
Know whether you’re selling wrapping or sourcing. If your value proposition is “let users buy what they otherwise couldn’t,” your real bottleneck is on the traditional-finance side, not onchain. Solve allocation relationships first. Don’t start by issuing tokens.
-
Put your upstream supplier’s delivery obligations in the contract, and disclose them to users. The four platforms could only apologize because they never made a clear commitment either way between “best-efforts delivery” and “guaranteed delivery.”
-
Don’t run tokenized IPOs on scarce assets without a confirmed allocation. Hot IPOs, pre-IPO equity, limited issues: if the platform takes money before locking in the underlying allocation, tokenizing these categories is bound to default exactly when demand peaks. The only exceptions are when the issuer allocates shares for onchain distribution directly, or when the platform gets the shares first and mints after. But at that point you’ve solved a sourcing problem, not a wrapping one.
Three lines to close
Tokenization is a wrapping technology, not a sourcing technology.
Demand can be manufactured onchain in an instant. Delivery can’t.
When the underlying is allocated by relationships, infinitely divisible tokens mean nothing.
What’s your take: can the tokenized IPO category be saved?
Repost this post?
Share with your followers.
Reply