Contents (6)

·
A 15-Day Subsidy Half-Life, 1.3 Billion Reward Tokens Worth $11,500, and a Real Risk Ledger
Reward-driven pools on Robinhood Chain take a median 15 days to fall by half from their peak, and one sponsor's 1.3 billion reward tokens were worth about $11,500. This piece separates fixed-total from fixed-rate subsidies, then builds a risk ledger with five fields per risk and runs four stress scenarios: a chain halt, a paused stock token, a Monday gap and a USDe depeg.
If you chase high-yield pools and points campaigns, or you already hold positions on Robinhood Chain, this piece answers two questions: when subsidies leave, how fast do money and yields fall; and when something breaks, how much do you lose and how long are you stuck?
15 Days
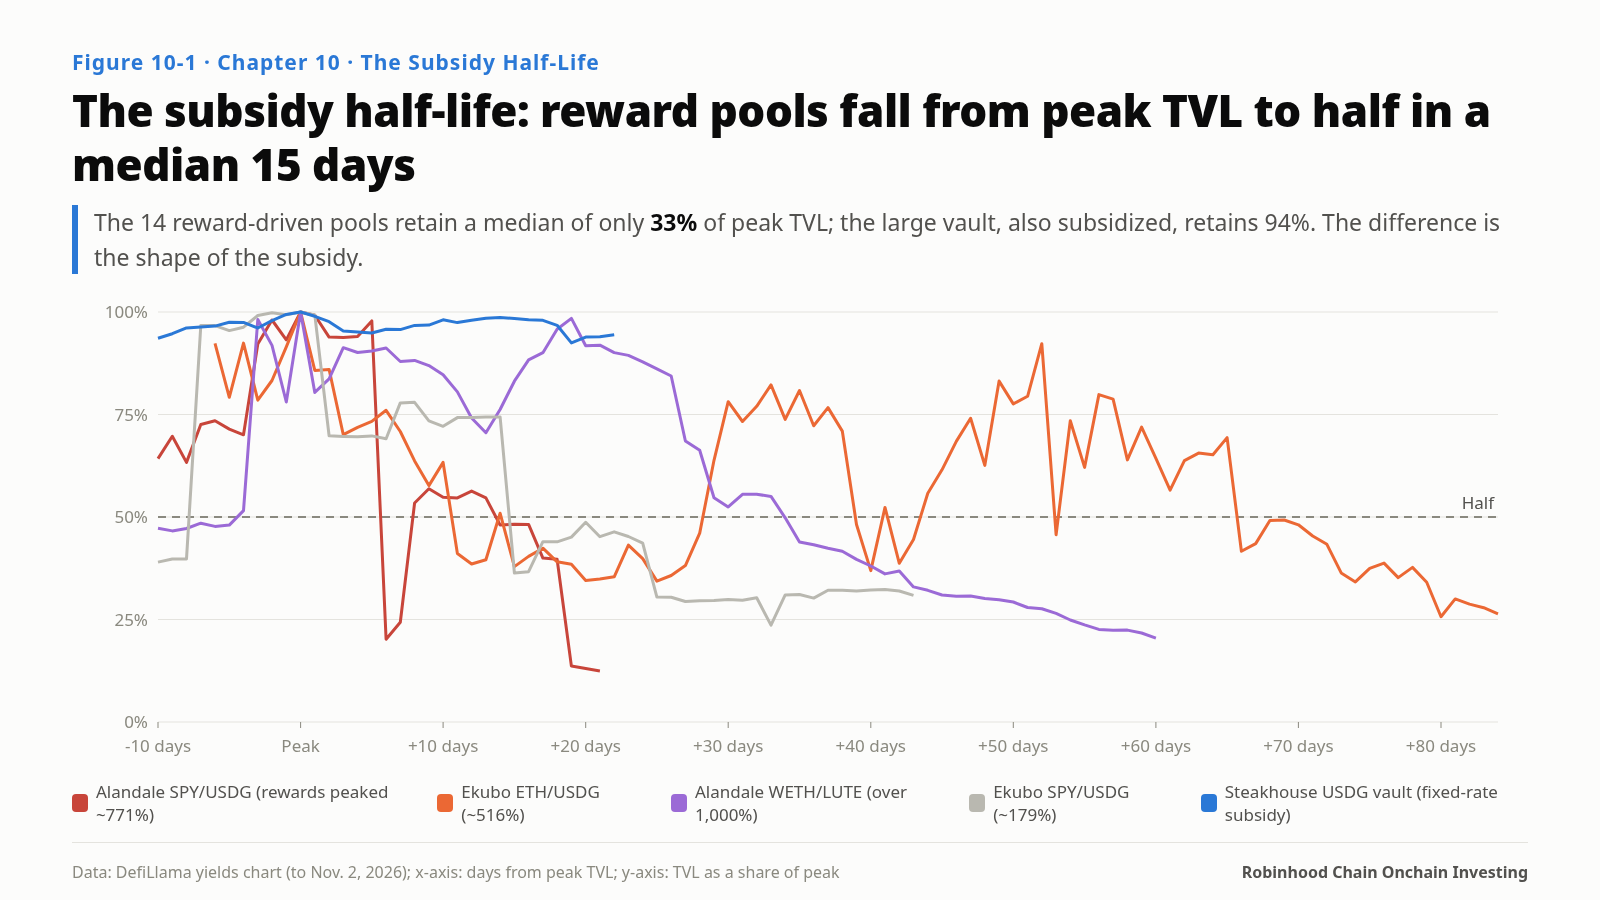
Group the yield pools DefiLlama tracks on Robinhood Chain by the share of yield that comes from rewards, then check how much TVL is left from each pool’s peak. Among the 14 pools where rewards are more than 80% of yield, the median pool retains 33% of its peak TVL; 11 have halved, and the median time from peak to half is 15 days.
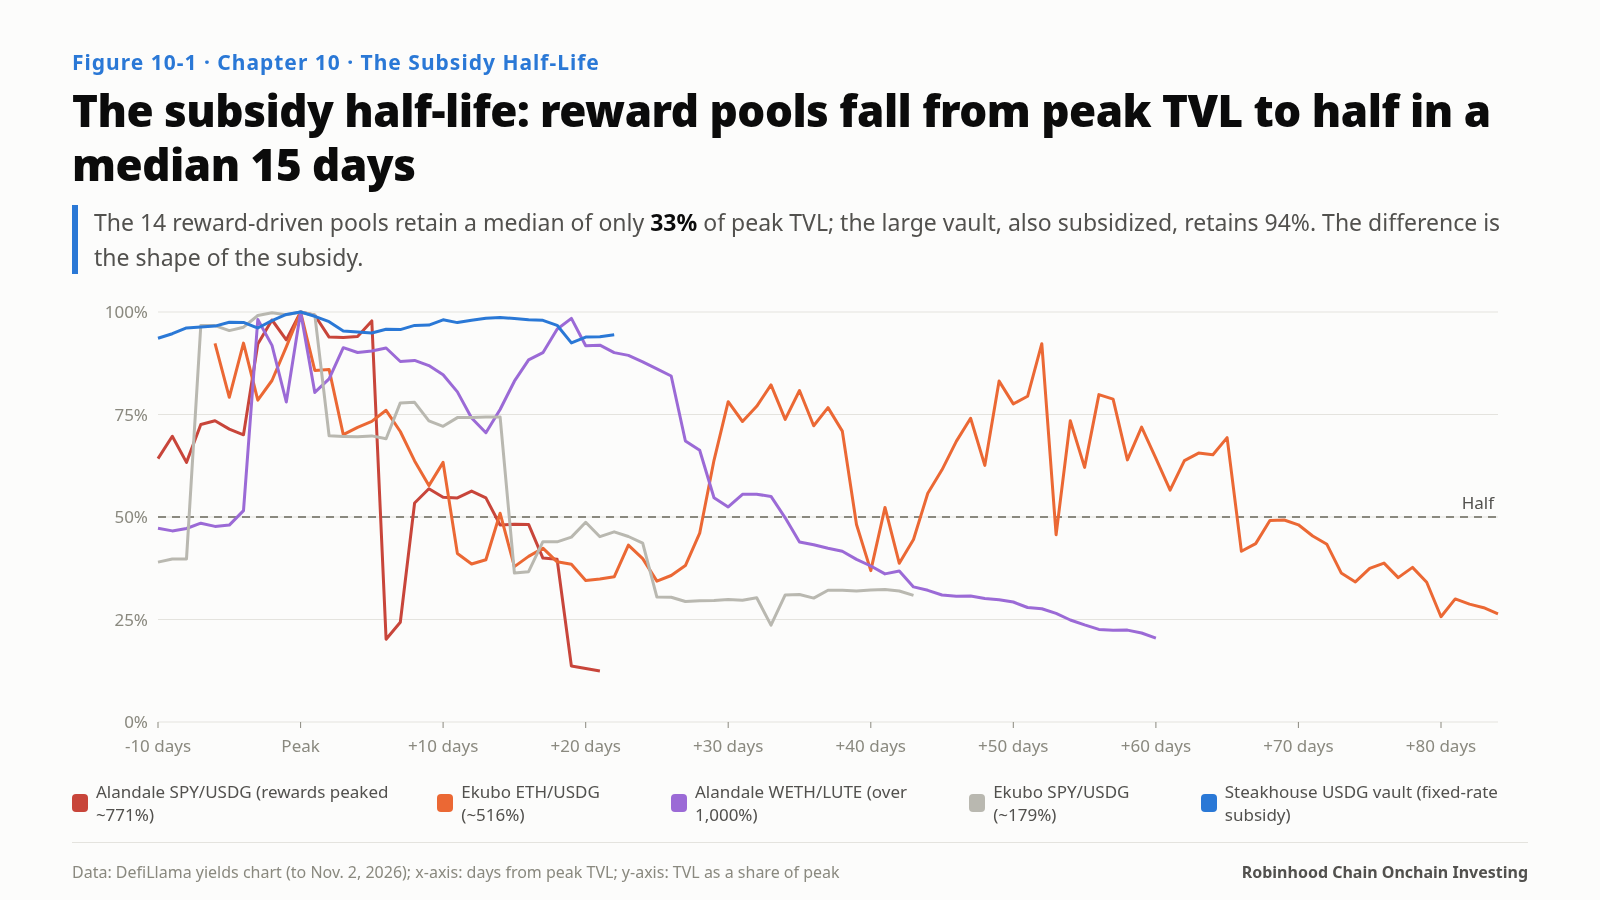
That is what I call the subsidy half-life: when a pool’s appeal comes almost entirely from rewards, money floods in when the reward is highest and half of it leaves within about two weeks.
Some examples: Alandale’s SPY/USDG pool peaked at a reward yield of about 771% and about $310,000 of TVL on October 12, halved six days later, and now retains 12%. Ekubo’s ETH/USDG pool peaked at a reward yield of about 516%, halved after 11 days, and retains 26%.
Why the Big Pools Don’t Halve
The same table has two exceptions: the Steakhouse USDG vault retains 94% of its peak and Morpho’s USDe market 95%. Their subsidy shares are not low, about 44% for the vault and 93% for the USDe market.
The difference is the shape of the subsidy.
- Fixed total. Small pools get a fixed amount of rewards, a few hundred dollars a day of UNI or a project token. The more TVL, the lower the yield. Early entrants get triple digits; money pours in, the yield collapses, and the money leaves. It is a self-terminating loop.
- Fixed rate. Robinhood’s Earn reward pays about 3% a year; Ethena’s USDe reward pays about 5% and resizes its budget weekly with the market, from 160,000 USDe a week in early July to about 520,000 by late October. The more TVL, the more the sponsor pays, and depositors’ yield stays the same.
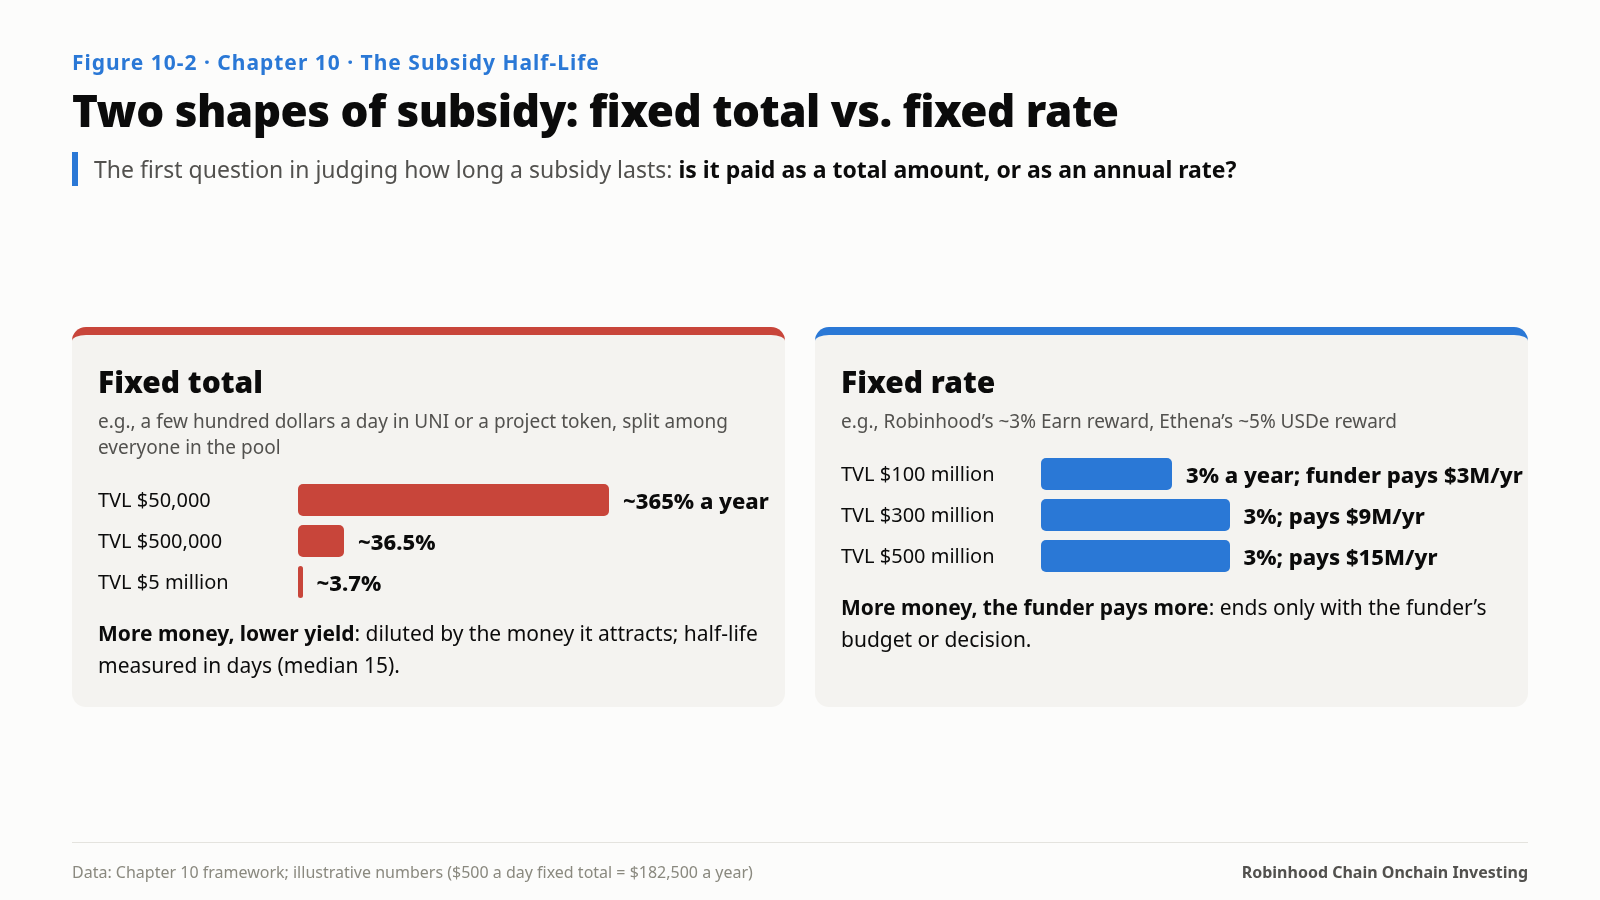
A fixed-total subsidy is diluted away by the money it attracts. A fixed-rate subsidy ends only when the sponsor’s budget does. The first has a half-life measured in days; the second’s depends on one company’s marketing decisions. To judge how long a subsidy will last, ask first: is it paid as a total or as a rate?
The Reward Itself Can Go to Zero
A tapering subsidy is not the worst case. The worst case is a reward that loses its value.
Merkl’s records show that from August 28 to November 2, one sponsor address launched 195 incentive campaigns on this chain paid in its own project token, EARN, covering multi-asset pools, market-making vaults, trading pairs and even lending markets. In total it paid out about 1.3 billion EARN. At early-November prices of about $0.0000088 each, those 1.3 billion tokens were worth about $11,500.
For comparison: Ethena paid about $5.26 million in USDe, protocols paid about $465,000 in USDG, and Uniswap paid about 45,500 UNI, worth about $330,000, to stock-against-stock pools.
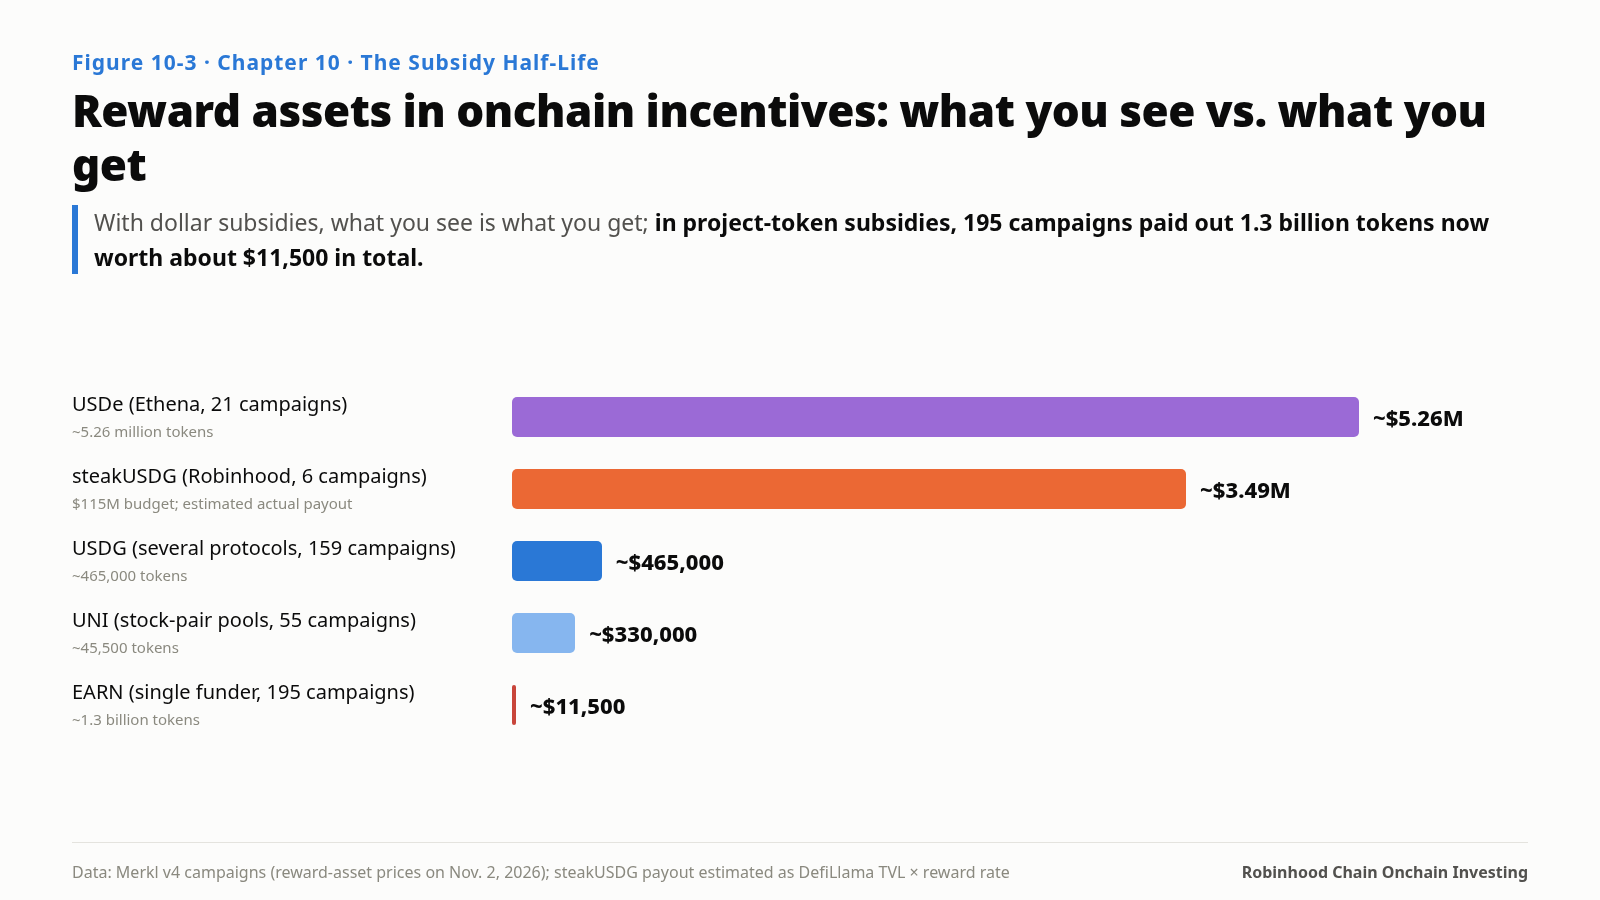
A subsidy paid in dollars or stablecoins is worth what you see. A subsidy paid in a project token shows you a yield priced at issuance and pays you a value priced at sale.
Points are another, invisible subsidy, best priced as an option. If a points campaign asks you to accept less than the 3.5–4% benchmark, the difference is your premium: 3 points below, $100,000 in, for six months, means you paid $1,500 for an airdrop lottery ticket. Ask yourself whether you would pay $1,500 for it outright.
Subsidies die in two ways: diluted by the money they attract, or switched off by the sponsor. Reward tokens have a third: going to zero before you sell.
Risk Lists Are Useless; Risk Ledgers Aren’t
“Smart contract risk, regulatory risk, liquidity risk.” Nearly every onchain investment report ends with a list like that. You can’t act on it: you don’t know which item matters more or how much you lose if it happens.
I record each risk with five fields instead:
Trigger · Has it happened · Worst loss · Time to exit · Can it be hedged
The first two say how real it is; the last three say how much it hurts. With those five fields, the chain’s risks fall into five layers: the chain, asset issuers, protocols, markets, and subsidies and access.
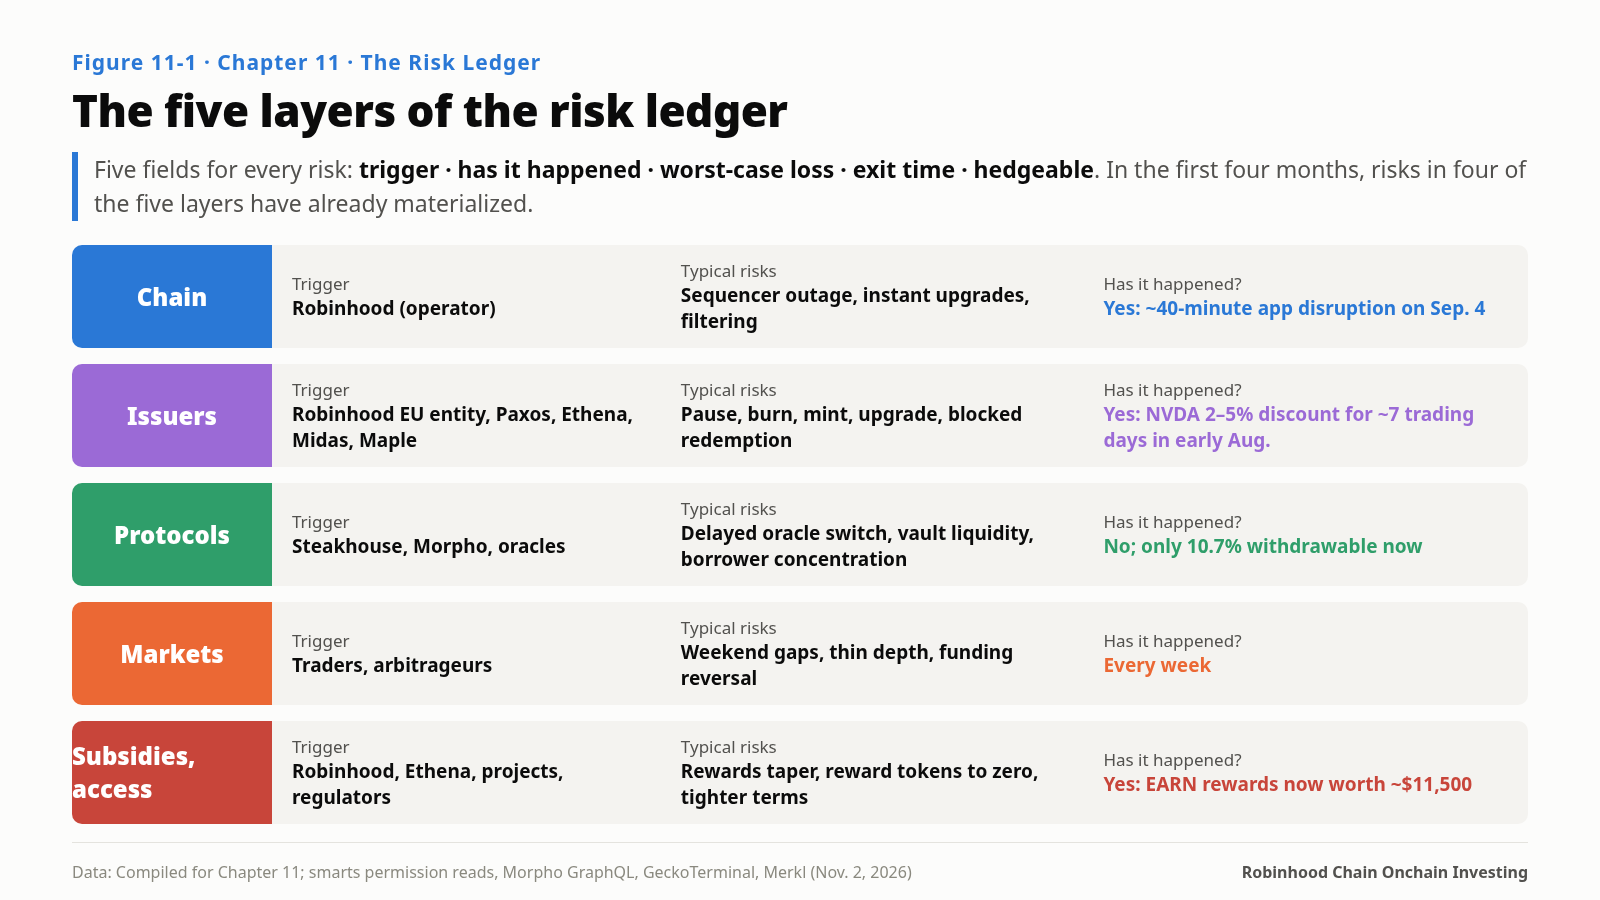
Recorded this way, the most useful column is “has it happened.” In the chain’s first four months, all of these did:
- An app outage. On September 4, successful transactions in busy apps fell to about a fifth of normal for about 40 minutes. When the chain layer fails, you can’t trade your way out: for spot holders and depositors the cost is a few hours’ delay; for leveraged positions it can be liquidation.
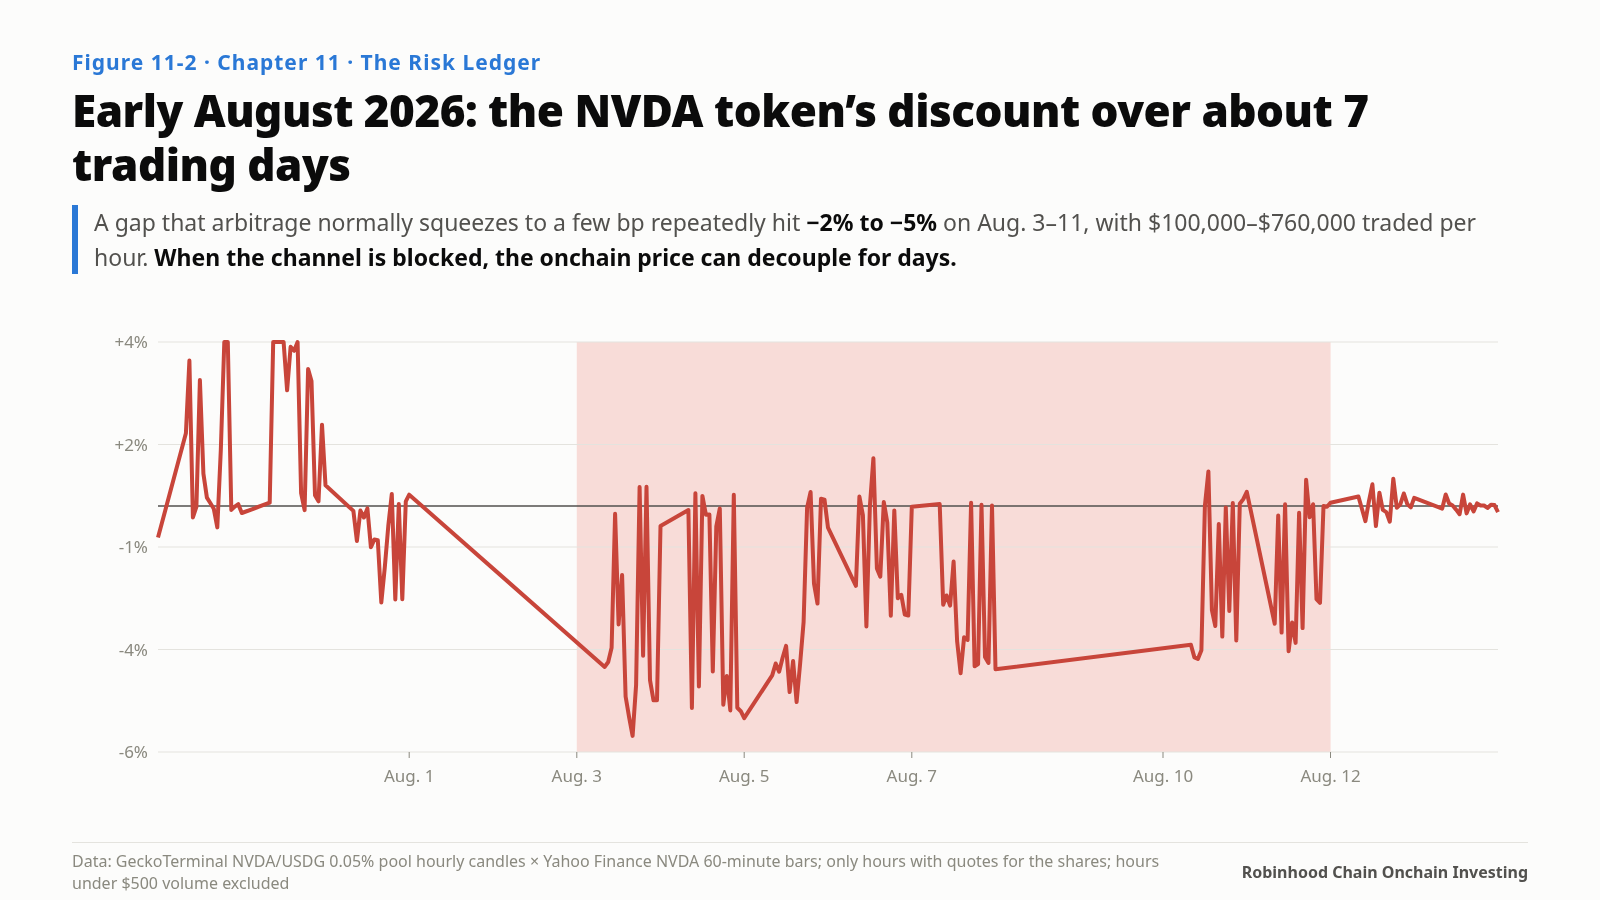
- A blocked arbitrage channel. From August 3 to 11, the NVDA token repeatedly traded 2–5% below the share during U.S. trading hours, on and off for about seven trading days. Normally that gap closes within a few basis points. “Arbitrage will pull the price back” assumes minting and redemption are open.
- Weekend gaps. Every week; the 95th percentile of weekend deviation runs from 83 to 321 basis points.
- A reward token going to zero. The EARN example above.
The issuer layer deserves its own entry. I read the main assets’ contract permissions: stock tokens are upgradeable, transfers can be paused, and an administrator can burn holdings from any address; USDG is upgradeable and pausable; mGLO is pausable; the vault’s curator can change allocations. Most of these powers have legitimate reasons, such as sanctions, corporate actions and bug fixes. But they mean that each asset’s worst case is decided not by the market but by a specific institution. Evaluating an asset means evaluating that institution too.
Four Stress Scenarios
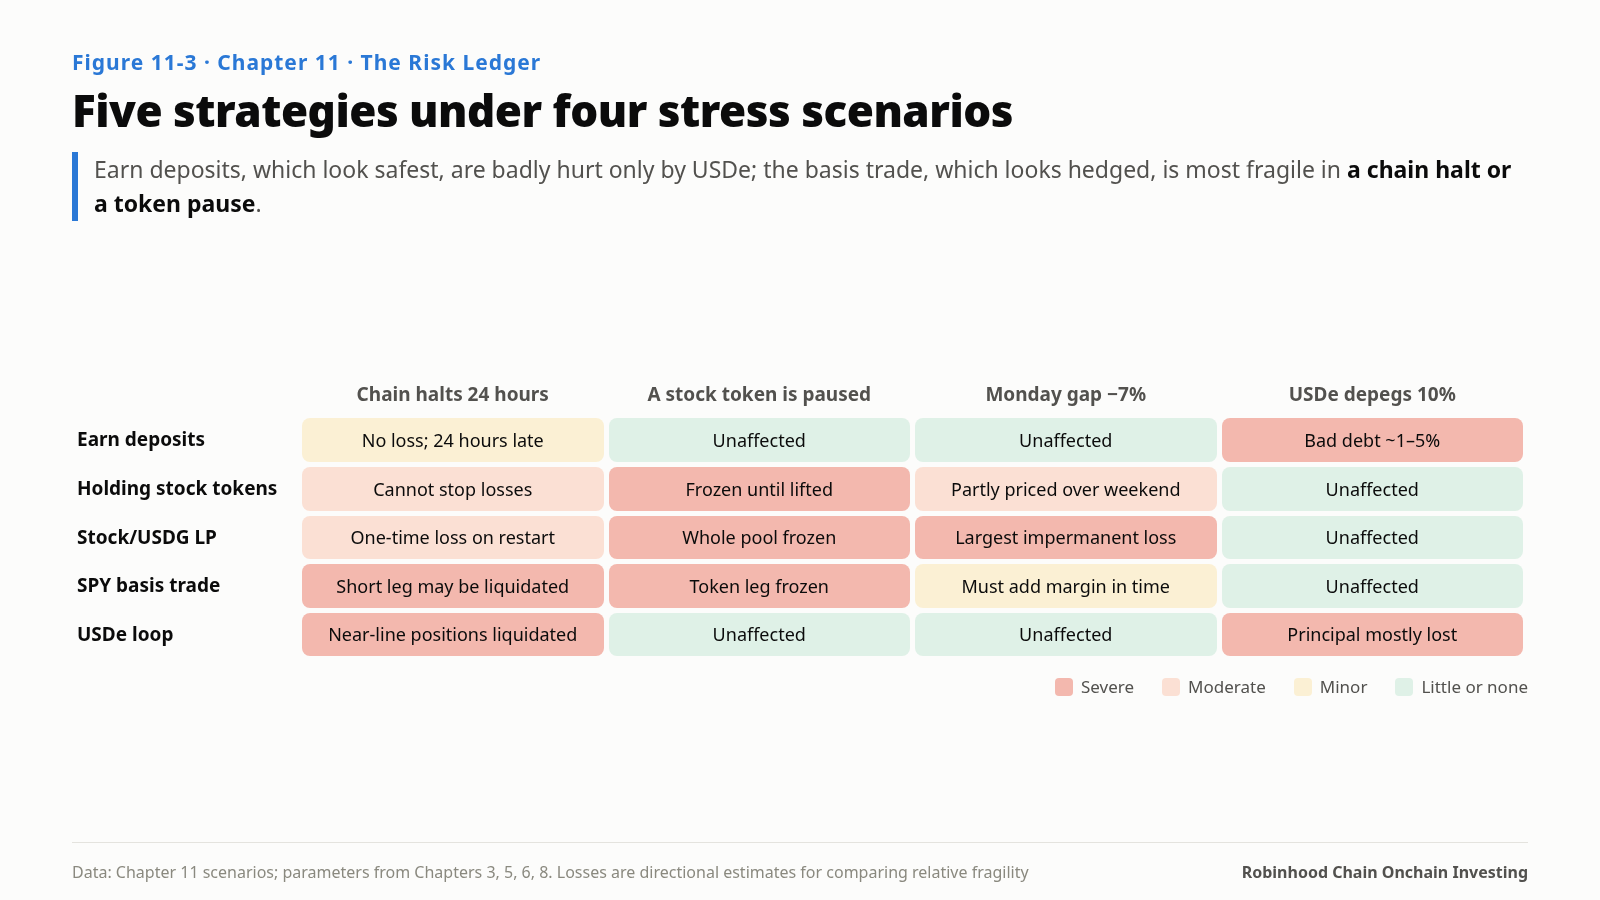
Combining the five layers, here is how the main strategies fare in four scenarios:
- The chain halts for 24 hours: deposits keep their principal but can’t be withdrawn. The basis trade suffers most: the perpetual short may be liquidated for lack of margin while the token leg can’t be sold.
- One stock token is paused: holders can’t sell, any LP pool containing it freezes, and lending markets using it as collateral can’t liquidate. Perpetuals and Earn deposits are unaffected.
- A −7% Monday gap: token holders who sold over the weekend lose less; stock/USDG LPs, filled with tokens by arbitrageurs all weekend, lose most; SPY/QQQ pools fall together and lose far less; perpetual longs at up to 50x are liquidated.
- USDe depegs 10% for 24 hours: for the first 16 hours the oracle still prices it at 1.0 and nothing is liquidated; after the switch, positions above about 89.6% LTV are undercollateralized. On a $520 million vault, depositors could lose about 1–5% pro rata, and loopers lose nearly all their equity.
If You Chase Subsidies or Manage Risk
- Ask the subsidy’s shape first. With fixed-total rewards, the later you enter the less you earn; a triple-digit yield over two weeks is roughly a one-time 3–5% before entry and exit costs.
- Prefer rewards paid in dollars; discount project-token rewards as if they may go to zero.
- Write the five fields for every position. If you can’t, cut the position first.
- Size leveraged margin for a chain halt: enough to survive at least one weekend gap, about 3% for SPY and 5–10% for single stocks.
- Diversify by trigger, not by product. Earn deposits, stock tokens and a USDe loop look like three strategies; two of them share one risk source.
A risk list tells you what could go wrong. A risk ledger tells you how much you lose and how long you’re stuck when it does.
Could you fill in the five fields for each position you hold?
—Adapted from Where the Yield Comes From: An Investor’s Handbook for Robinhood Chain, Chapter 10, “The Subsidy Half-Life,” and Chapter 11, “The Risk Ledger”
The full book (15 chapters, 42 figures): https://pickful.ai/books/dgpy
Repost this post?
Share with your followers.
Reply