Contents (5)

·
Math First: UNI tripled in six weeks. Its market cap, not the rally, rules out a 10x
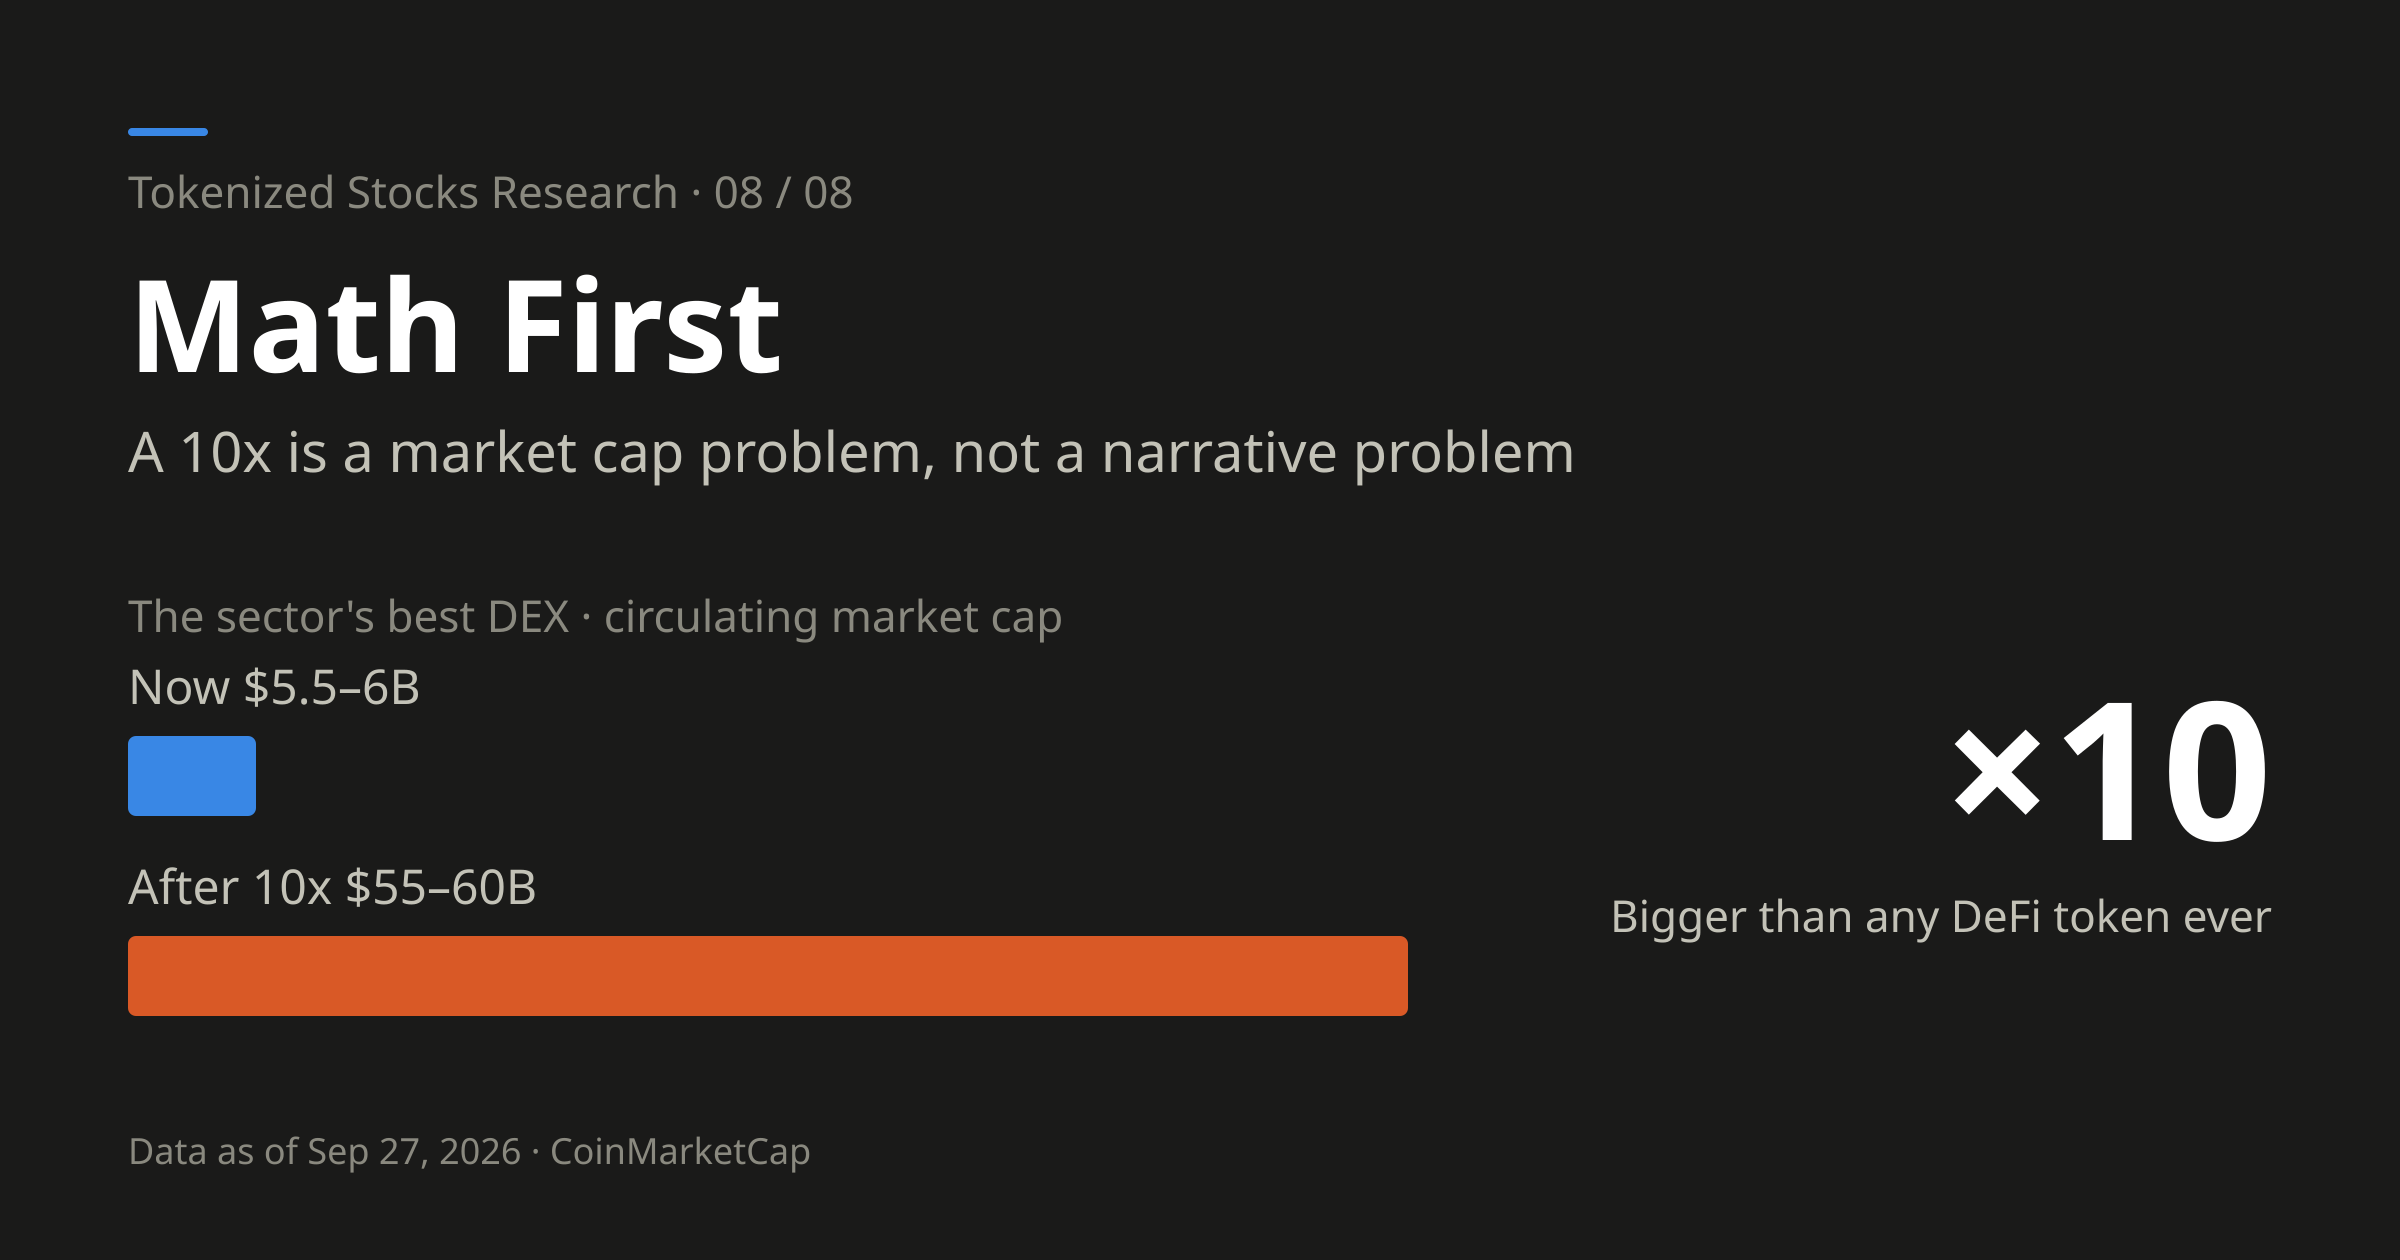
A 10x is a market cap problem, not a narrative problem. Calculate the post-10x market cap, compare it with the category's historical ceiling, and only then look at fundamentals. Run through tokenized stocks, the two best businesses aren't 10x candidates.
If you’re hunting for high-multiple names, this is about the first step most people skip.
A 10x is a market cap problem, not a narrative problem.
However right a thesis is, it can’t turn a $6B token into a $60B one. Yet nearly every “10x candidate” analysis out there starts from the narrative and never does this step.
Math first: three steps
Step 1: Calculate the market cap after a 10x. Not the price. The market cap.
Step 2: Compare that number with the historical ceiling for the asset class. If the post-10x market cap is bigger than the largest asset that category has ever produced, it has to set a new record. Default: eliminated, however good the thesis.
Records do get broken. But breaking one needs a specific reason: the category itself is getting bigger, or this asset has a value-capture mechanism its predecessors didn’t. “The thesis is good” isn’t that kind of reason. This step isn’t a mathematical impossibility. It’s a very high bar.
Step 3: Only look at fundamentals for names that pass the first two steps.
Don’t reverse the order. If you do, you’ll confuse a good business with a good trade.
Running the tokenized stock sector through it
I’ve done full research on this sector, and I think the thesis holds. Running the three steps over it gives this:
| Asset type | Circulating market cap | After 10x | Feasibility |
|---|---|---|---|
| The sector’s best DEX | $5.5–6B | $55–60B | ❌ Bigger than any DeFi token ever |
| The de facto standard oracle | ~$8–9B | $85B | ❌ Would need a top-5 spot overall |
| Leading lending protocol | $1.8B | $18B | ❌ Very hard |
| L2 tech stack | $1.4B | $14.1B | ⚠️ Needs to get back to its historical highs |
| Leading perps venue | $926M circulating / $3.7B FDV | $9.26B circulating / $37B diluted | ⚠️ FDV is the binding constraint |
| Leading Solana credit protocol | $157–246M | $1.6–2.5B | ✅ Mathematically feasible |
The conclusion isn’t romantic: the two best businesses in this sector are not 10x candidates.
That DEX went from $3.20 to $9.69 in six weeks, roughly a 3x. What rules it out isn’t that rally. It’s the market cap after it: $5.5–6B times 10 is a level no DeFi token has ever reached. Buying it now is buying a good business, not buying a 10x.
Three traps this step helps you avoid
Trap 1: FDV.
The perps venue in the table is a textbook case: $926M circulating, $3.7B FDV, a 4x gap, with only 25% of supply circulating.
About 166M tokens unlock each year, while buyback-and-burn from revenue removes about 30.6M. Burns absorb only 18% of new supply, so net issuance equals 54% of current circulating supply per year.
Against about $86M in annualized fees, that’s 14x on circulating and 56x fully diluted.
A 10x on circulating market cap means a $37B FDV. You have to beat your own unlock schedule first.
Trap 2: Revenue that doesn’t accrue to the token.
The L2 tech stack’s revenue is real: under the Arbitrum Expansion Program it takes 10% of net protocol revenue from outside chains, and Robinhood Chain pushed its run rate to about $5M a month, more than 5x a few months earlier. Standard Chartered put out a 2030 price target 70x higher.
But Standard Chartered’s own report says holders have no direct claim on that revenue. The money goes to the DAO treasury (8%) and the Developer Guild (2%). Holders get none of it unless governance votes in a distribution mechanism, and that vote has never happened.
So this isn’t a fundamentals trade. It’s a governance-event trade. The two need completely different holding periods and stop-loss logic.
Trap 3: Negative correlation.
The name with the strongest current cash flow in the sector is a memecoin launchpad: peak 24-hour fees near $6M, a 30-day gain of more than 2,700% at one point, 80% of protocol fees going to buyback-and-burn, about 30% of total supply already burned.
But if the sector’s thesis plays out, it’s the one that gets displaced.
The thesis is “tokenized stocks take over.” If that happens, memecoins’ share should fall the way it did on Solana, from 79% of DEX volume to 20–30%. It’s a bet on the casino boom. It hedges the thesis rather than expressing it.
Plenty of people put “thesis names” and “thesis hedges” in the same basket. That isn’t diversification. It’s hedging against yourself.
One last discipline on the numbers
After a name passes the math, there’s one more check: is the market cap itself credible?
The last name in the table has a market cap that varies from $157M to $246M depending on the data source, a 57% gap.
That isn’t a data error. It’s direct evidence of thin liquidity. At this size, your buy orders push up your own cost, and your sell orders hit through your own bid.
Room for a 10x on paper and the ability to actually capture one are two different things.
Three lines to close
Calculate the post-10x market cap first, then look at the narrative. Reverse the order and you’ll mistake a good business for a good trade.
FDV, value capture, and correlation with the thesis: these are the three gates after the math.
And at the level where market cap data can differ by 57%, room to run and the ability to execute are two separate questions.
When you screen for high multiples, what’s your first step?
Repost this post?
Share with your followers.
Reply