目录(6 节)

·
Seven Tollbooths: Only 0.1% of a Launchpad's Own Token Trades Go Through Its Website
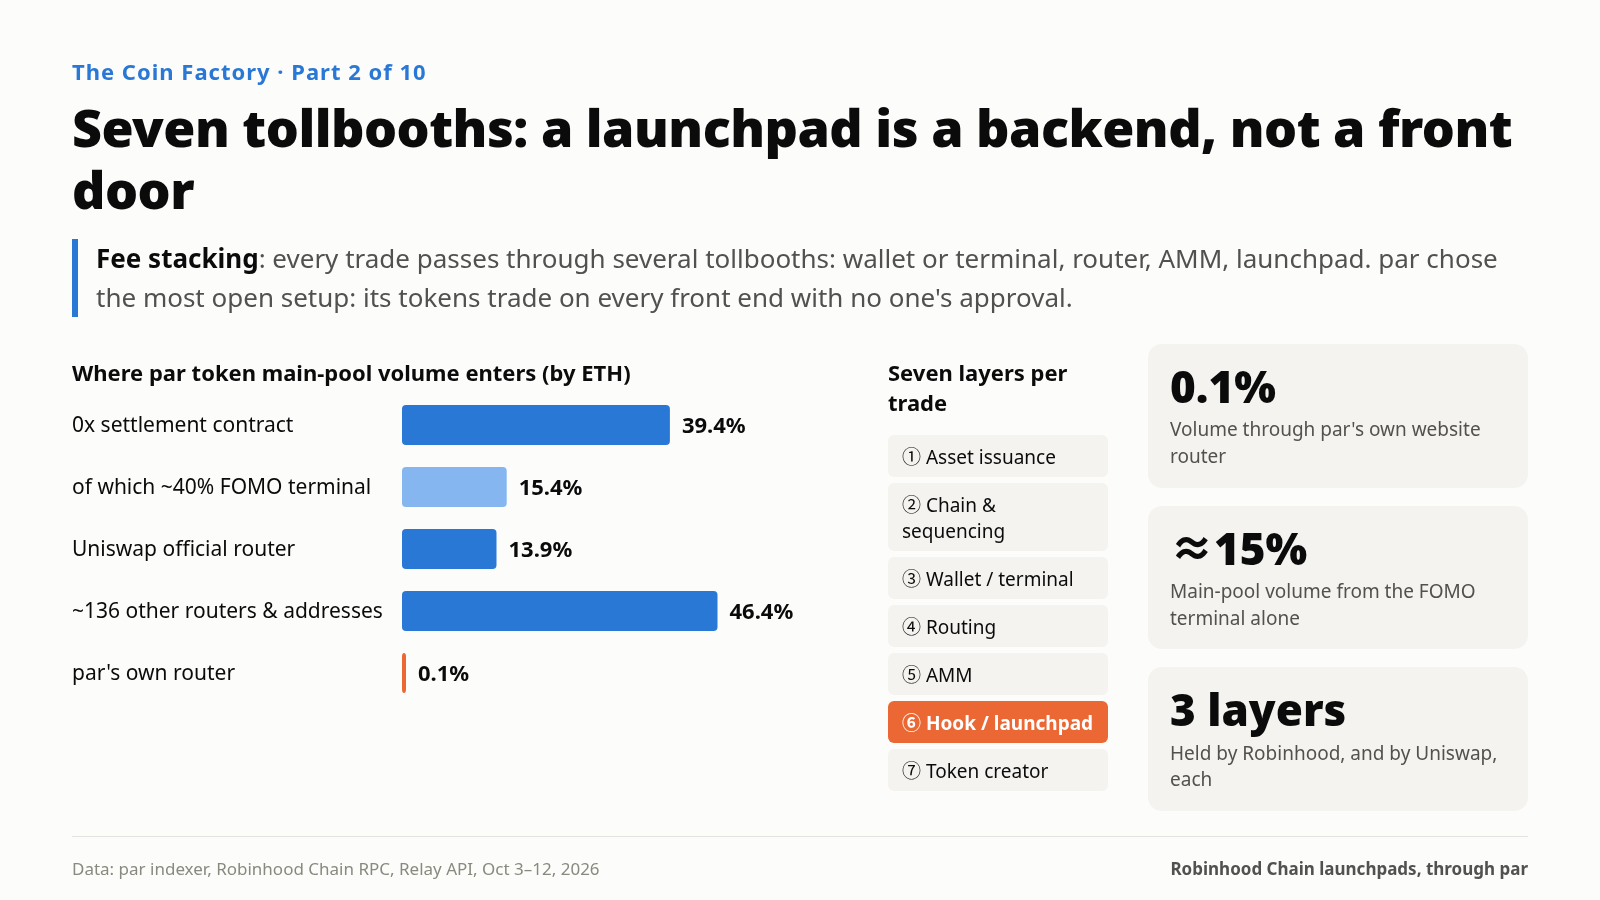
Only 0.1% of par's platform token main-pool volume goes through its own router; 39.4% comes via 0x, about 40% of that from the FOMO terminal. A seven-layer map of who collects what on Robinhood Chain, the fee-stacking framework, and where pricing power sits.
If you’re evaluating an app on a new chain, or trying to decide whether a launchpad can make money over the long run, don’t start with its fee rate. Start by checking where its users come in.
par.family, a launchpad on Robinhood Chain, has a full trading interface on its website and its own router contract, PairPadRouter. We pulled the latest 2,000 trades in its platform token’s main pool, from October 3 to 11 (par’s official indexer), and broke down ETH volume by entry point:
| Entry contract | Share of volume | What it is |
|---|---|---|
RobinHoodSettler |
39.4% | 0x’s general-purpose settlement contract on this chain; every app that uses 0x goes through it |
Uniswap UniversalRouter (two deployments) |
13.9% | Uniswap’s official router, covering its web app, wallet and API |
| Other aggregators, terminal routers and addresses (~136) | ~46% | |
par’s own PairPadRouter
|
0.1% | The launchpad’s official router |
(Contract names come from verified source on Blockscout. The indexer only covers the main pool created at launch; per DexScreener, that pool accounts for a bit over 70% of the token’s total volume.)
99.9% of a launchpad’s own token volume never touches the launchpad’s interface. On this chain, a launchpad isn’t the user’s front door. It’s a backend that other people’s front doors call.
The biggest slice, 39.4%, is worth opening up. This 0x settlement contract is 0x’s general contract on the chain; any app integrated with 0x routes through it, so the “RobinHood” in its name refers to the chain, not the wallet. Using the same method on data from October 3 to 12 (2,000 trades in the main pool, about 75.5 ETH, 38.4% via 0x), we traced each of the 410 trades that went through 0x back to its outermost layer:
| Outermost path | Share of the 0x slice | Who |
|---|---|---|
| Filled by a Relay solver | 20.2% | Looked up via Relay’s API: of the 90 orders found, 86 were tagged with source app “fomo,” nearly all placed on Solana with USDC |
| EIP-7702 wallets routed via Relay | 22.3% | 71 accounts with identical technical fingerprints; 20 of them are the recipient addresses on those FOMO orders |
| EIP-7702 wallets, Alchemy account contract | 36.9% | 13 accounts, no overlap with FOMO addresses; source app not confirmed |
| Regular wallets calling the 0x API directly | 6.0% | |
| Other | 14.6% |
Put together, about 40% of the 0x volume comes from the trading terminal FOMO, which works out to roughly 15% of main-pool volume. The portion directly confirmed as FOMO is at least 8% of the main pool. Every FOMO trade is Relay calling 0x, so on-chain it looks like 0x, but behind it is a terminal. Robinhood Wallet’s share can’t be separated out on-chain, but it can’t exceed what’s left.
Seven layers
Line up everyone involved in a single meme trade, from the bottom of the stack to the user:
| Layer | Who | What they charge | What power they hold |
|---|---|---|---|
| ① Asset issuance | Stock token issuer Robinhood Assets (Jersey); stablecoin USDG | Issuance and redemption | Stock token contracts can pause, blacklist, and let an admin burn from any address |
| ② Chain and sequencing | Robinhood (sequencer); Arbitrum (tech license) | Gas; under the license, 10% of net protocol revenue goes to the Arbitrum side | Transaction ordering; contract upgrades controlled by a Robinhood multisig |
| ③ Front ends | Robinhood Wallet; terminals like GMGN, Axiom, FOMO | Terminal trading fees | Which tokens users see and which pools they can trade |
| ④ Routing | 0x, Uniswap routing API, terminal routers | Spread or routing fee | Which pool the order flows to |
| ⑤ AMM | Uniswap v2/v3/v4 | Protocol share of pool fees | All v4 pools share one PoolManager contract that custodies assets |
| ⑥ Hooks and launchpads | Pons’s hook; par and PAIR pools; pools.trade | ~0.25%–1% per trade | Launch rules, fee splits |
| ⑦ Token creators | Whoever launched the token | Creator share; on par, an optional tax of up to 10% | Their token’s narrative and community |
Two things stand out.
Robinhood holds three layers: it issues the stock tokens, it runs the chain and the sequencer, and it owns Robinhood Wallet. It doesn’t currently have its own launchpad.
Uniswap also holds three: it’s the chain’s main AMM; it decides which hooks get into its router (more on that in the next piece); and on August 5 it launched its own launchpad, pools.trade. On top of that, per The Block and others, Uniswap governance voted in late July to extend the protocol fee to Robinhood Chain, so since July 27 a portion of Uniswap pool volume on this chain flows into UNI buyback-and-burn.
The launchpad sits in the middle: front ends above, rails below, asset issuers off to the side.
Fee stacking
A retail trader buying a meme token launched on par through a trading terminal pays, in order:
| Tollbooth | Rate | Who gets it |
|---|---|---|
| Trading terminal | ~0.5%–1% (third-party roundups put GMGN and Axiom at ~1%, FOMO at ~0.5%) | Terminal |
| Pool fee | 1% | Split evenly between par’s creator and the protocol |
| Creator tax (optional) | 0–10% | Creator |
| Gas | A few cents | Sequencer |
| Bridging (when the terminal fills via cross-chain intents) | Bridge fees, plus front-running risk | Bridges and solvers |
That’s the framework for this piece:
Fee stacking: every trade passes through several tollbooths at once: a wallet or terminal, a router, an AMM, a hook or launchpad. The launchpad thinks it’s the tollbooth. It’s just one of them, and the one farthest from the user.
What the terminal charges is in the same range as what the launchpad charges, sometimes more.
Bridging adds costs you can’t see. A Bitquery investigation found that from September 12 to 25, three groups of bots exploited the gap between when a FOMO user’s order was recorded by the cross-chain protocol Relay and when it was filled. They bought first, then sold into the price the user pushed up. In total they front-ran 3,532 orders involving $6.5 million; measured against Relay’s quotes to users, users lost about $181,000. That money isn’t any layer’s “fee,” but it left users’ pockets all the same.
Which layer has pricing power
In a stacked structure, pricing power belongs to the layer that’s hardest to replace.
Launchpads are the easiest to replace. There are about 30 on the chain, most of their contracts are open source, and par’s own code comments say it’s adapted from the Pons V2 contracts. par and pools.trade both launch standard Uniswap v4 pools that any terminal can trade directly. Switching launchpads costs a user almost nothing.
Front ends are the hardest to replace. Funds, habits, friends’ activity and trade history all live in the wallet or terminal. In par’s platform token main pool, FOMO alone contributes about 15% of volume, while par’s own website does 0.1%.
The rails are close to irreplaceable. There’s one sequencer. The main AMM is Uniswap, and every v4 pool shares one PoolManager.
That’s why pools.trade can cut fees to 0.25% and charge no launch fee. Uniswap doesn’t need to make money at the launchpad layer; it already earns at the AMM and routing layers, more so now that the protocol fee switch is on. As Decrypt put it bluntly, zero fees are a choice very few teams can afford.
Applying it to par
par has concentrated its effort on layer ⑥ and built it out further than anyone: quote in any asset, multi-market pairing, fees that can go to holders or become a price floor, fees that can be paid straight to an X account. It has more features here than any of its peers. It chose standard, hook-free Uniswap v4 pools, which means every token it launches can be traded by every wallet, terminal and aggregator without anyone’s approval. FOMO alone contributes about 15% of platform token main-pool volume, and par did no special integration to get it.
The advantage of this path is openness: the more front ends there are, the more places par tokens get traded. The next room for growth is just as clear: deeper integration with the front-end layer, such as full par token info displayed in major terminals, and turning capabilities others can’t easily offer, like any-asset quoting and a programmable interface, into default tools for other communities and AI agents. Later pieces cover both.
Three checks for any app on a new chain
1. Ask where users come in. Look at which router contracts a token’s or platform’s volume comes from. If most of it comes through other people’s wallets and terminals, the platform has weak bargaining power.
2. Include terminal fees in the user’s cost. The gap between a 0.25% and a 1% launchpad fee can get swamped by a 1% terminal fee.
3. Find the players that hold several layers. On Robinhood Chain that’s Robinhood and Uniswap. Every step either takes into the launchpad layer reshapes it; pools.trade was the first.
Closing
Money moves from a user’s pocket onto the chain through seven layers.
The launchpad stands in the middle and sees all of it, yet holds the layer that’s easiest to swap out.
Its long-term position depends on which front end it can tie itself to.
When you trade on a new chain, do you use a wallet, a terminal or the project’s own site? Why?
— Excerpted from Chapter 2 of The Coin Factory, “Who Collects This Chain’s Money”
转发此帖子?
与您的关注者分享。
回复