Dividends, Splits and Multipliers
At 17:57 UTC on November 16, 2026, during the US session, SPY was at $743.26. In the same minute, six SPY tokens on-chain were priced as follows:
- Ondo (Ethereum): $752.30, 1.22% above the underlying;
- xStocks (Ink): $750.81, 1.02% above;
- xStocks (HyperEVM): $749.99, 0.91% above;
- xStocks (Solana): $748.97, 0.77% above;
- Robinhood (Robinhood Chain): $745.65, 0.32% above;
- bStocks (BNB Chain): $745.41, 0.29% above.
Looking only at these numbers, you would conclude that Ondo’s SPY is 1.2% expensive, nearly 1 percentage point dearer than bStocks, and worth a cross-issuer arbitrage trade.
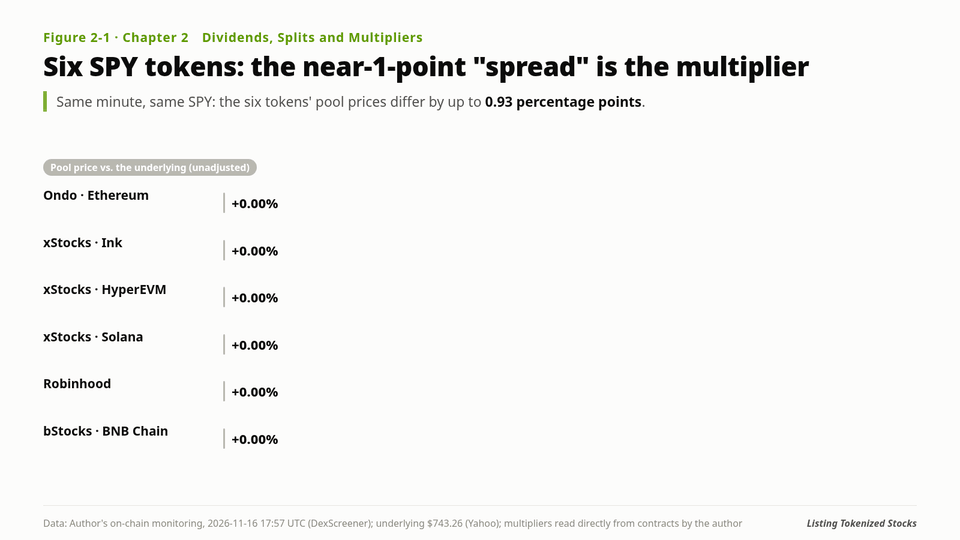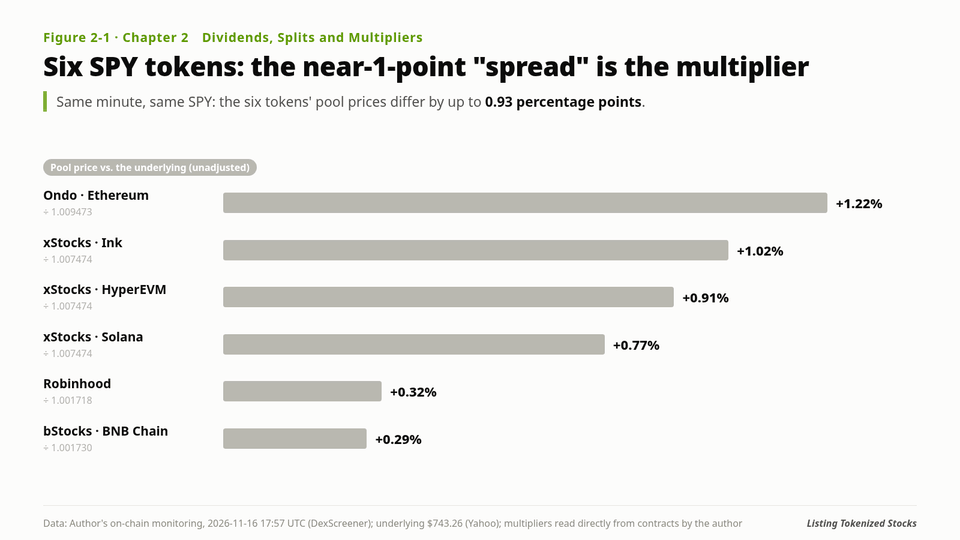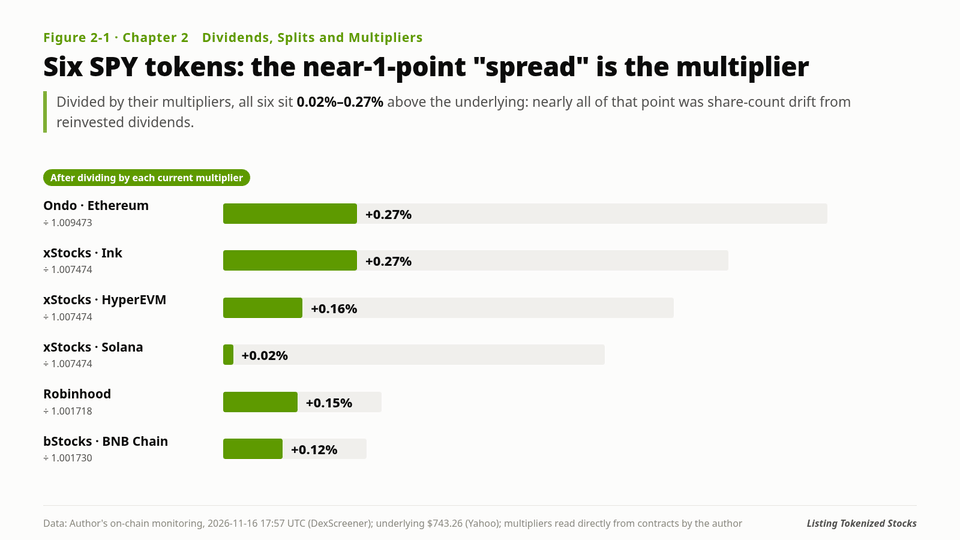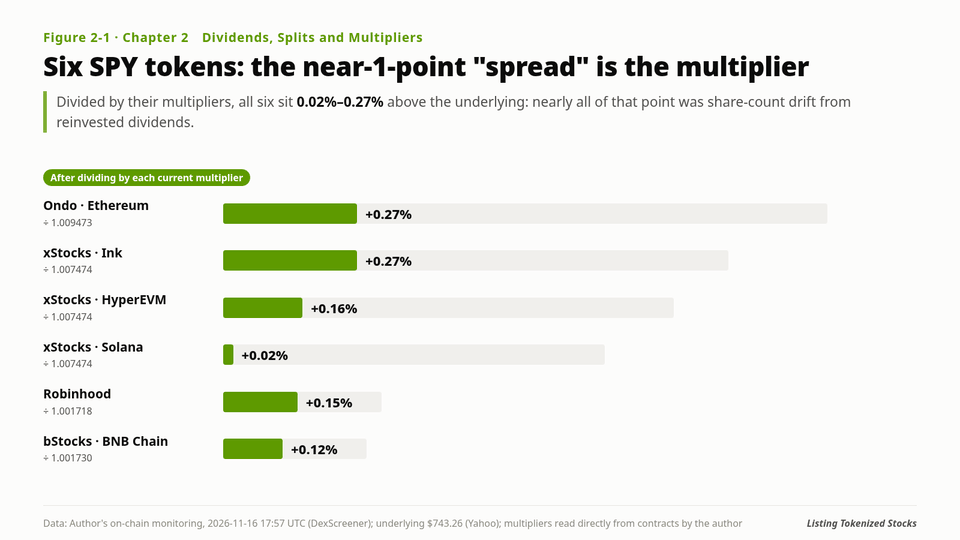
That conclusion is wrong. Across the six tokens, “1 SPY token” represents a different number of shares: one Robinhood or bStocks token is about 1.0017 shares, one xStocks token about 1.0075 shares, and one Ondo token about 1.0095 shares. Divide each price by its multiplier and the deviations fall to between +0.02% and +0.27%. Nearly all of that “spread” of almost 1 percentage point is a difference in share count left behind by reinvested dividends.
The decision this chapter asks you to make is: which number your system uses to represent “1 token = how many shares,” which contract and which field it reads that number from, and how it behaves in the few minutes around a corporate action. It looks like an engineering detail, but it drives display prices, quotes, collateral valuation and reconciliation. Read it wrong once, and a profit or loss that does not exist appears in the books.
All on-chain readings in this chapter were taken by the author directly from contracts between 17:50 and 18:10 UTC on 2026-11-16 (Solana public RPC, public RPCs for each chain, smarts). Prices are DexScreener pool prices; see Chapter 4 for the methodology.
1. How corporate actions flow through to the token
None of the four issuers compared in this book pays cash, issues new shares or lets holders vote (issuers with other structures, such as Dinari and Securitize, differ; see Chapter 1). All four handle corporate actions in the same basic way: everything is converted into “shares per token,” and that number is the multiplier. At launch the multiplier is 1. After each dividend, the issuer uses the dividend (net of withholding tax) to buy more of the underlying stock and raises the multiplier; after each stock split, it adjusts the multiplier by the split ratio.
The differences are in the details, and each one maps to a field or a calculation step in your system:
| Corporate action | xStocks (Backed) | Ondo Global Markets | bStocks (BTech) | Robinhood (RHJ) |
|---|---|---|---|---|
| Cash dividend | Reinvested after tax; multiplier raised | Reinvested after tax; sValue raised | Reinvested after tax; multiplier raised | Reinvested after tax; multiplier raised |
| When it takes effect | Activated at 00:30 UTC the day after the ex-dividend date | Trading may be paused 19:50–20:10 US Eastern the day before the ex-dividend date | Website says “reinvested on the ex-dividend date”; FAQ says “multiplier updated shortly after the record date”; the two disagree | Trading usually paused during processing |
| Split / reverse split | Multiplier scaled up / down proportionally | sValue adjusted proportionally; price frozen during the process | Multiplier adjusted; deposits, withdrawals, conversions and spot trading all paused | Multiplier adjusted; paused during processing |
| Mergers, spin-offs, delistings | Website says only “handled according to the product terms and the outcome of the corporate action” | Not stated in documentation | May be handled via the multiplier, reinvestment, sale of property, cash substitution, etc. | During a delisting, only selling or redemption may be allowed |
(Sources at the end of the chapter. “Not stated” means the issuer’s public documentation did not cover the item when checked on 2026-11-16; it does not mean no arrangement exists.)
Three points deserve separate attention.
First, dividends arrive at a discount. All four “reinvest after deducting applicable withholding tax.” The default US withholding rate on dividends paid to non-US persons is 30%. Chapter 6 of Where Does the Yield Come From traced the multiplier changes of five Robinhood tokens: each multiplier increment was almost exactly 0.69 times the dividend yield, consistent with 30% withholding plus about 1% in processing costs. The bStocks prospectus states that dividends are reinvested after deduction of 30% US withholding tax, and the example in Ondo’s user FAQ also uses the 30% default rate. Dividends do not vanish inside the token; about 30% is taken off first, and the rest becomes more shares. For high-dividend stocks that is a real cost of more than one percentage point a year, and the product page should say so (Chapter 1 covers disclosure).
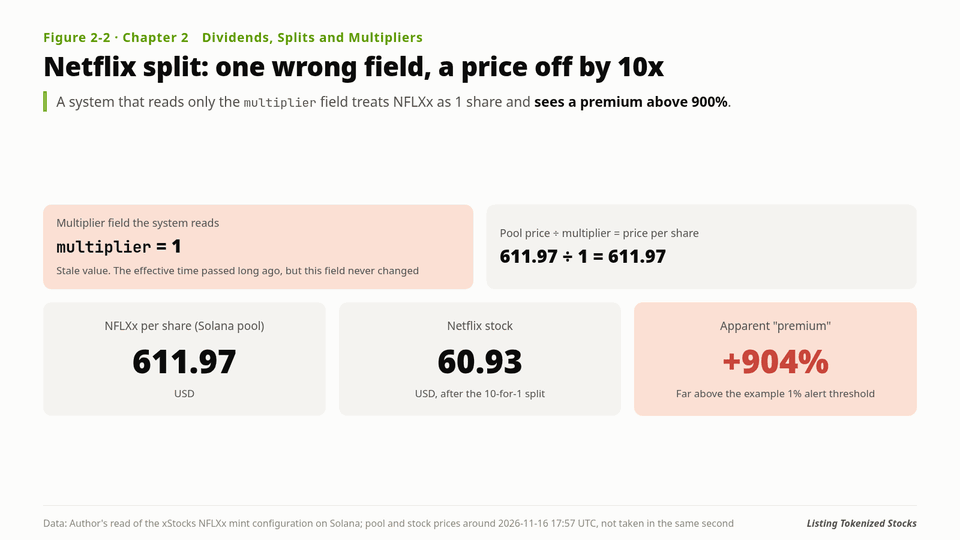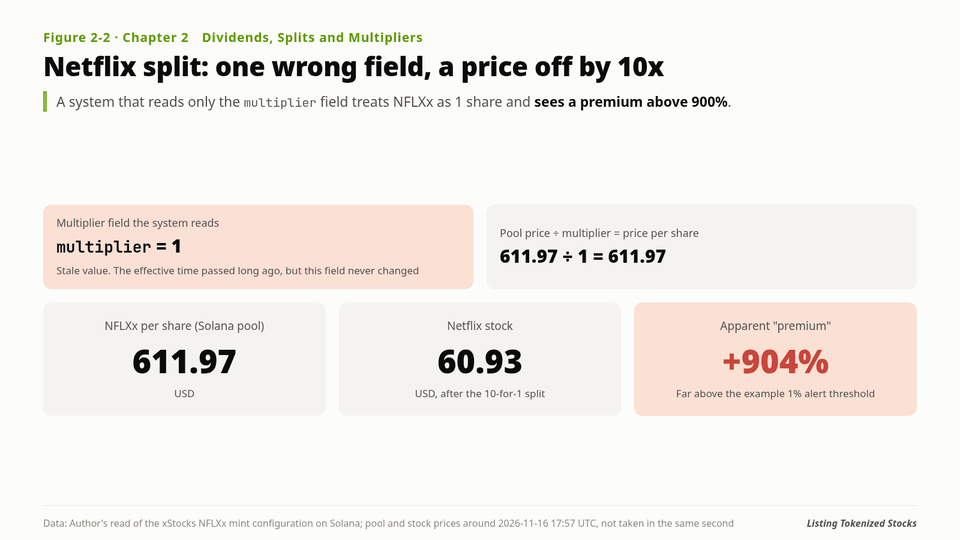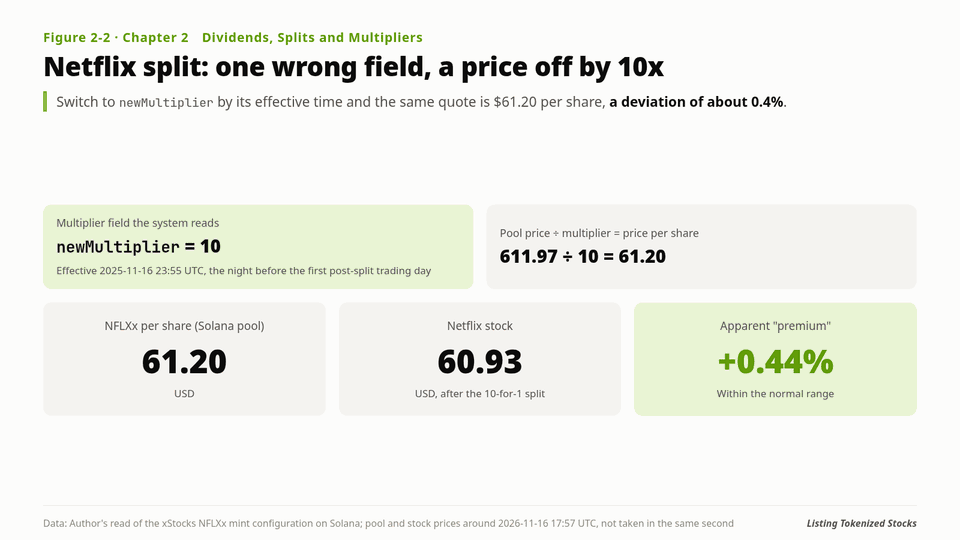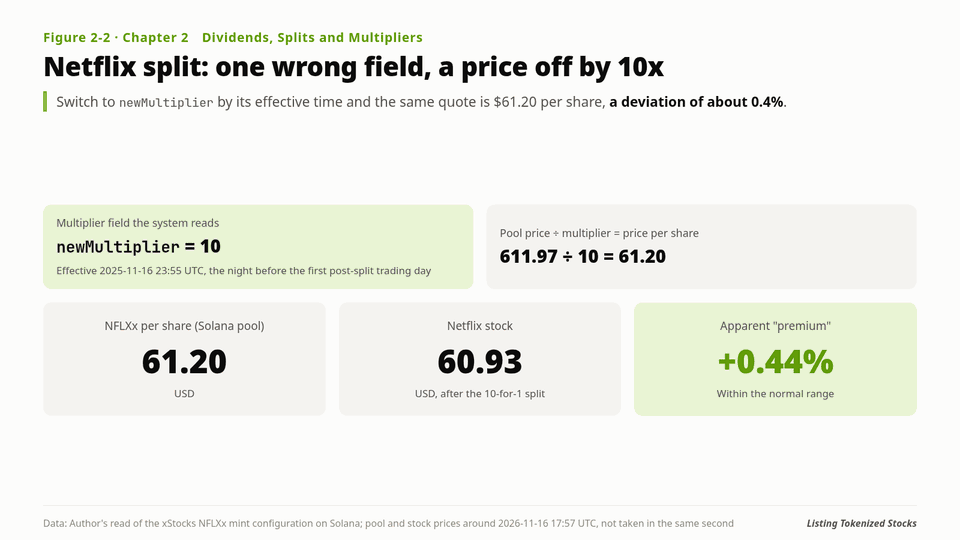
Second, splits have a real precedent. Netflix did a 10-for-1 split in November 2025, with post-split trading starting on November 17. We read the configuration of xStocks’ NFLXx on Solana: the new multiplier is 10, effective at 23:55 UTC on 2025-11-16, the night before the first post-split trading day. Around 17:57 UTC on November 16, NFLXx was quoted at $611.97 in a Solana pool, while Netflix stock was $60.93. A system that does not understand the multiplier would read this as a 900% premium.
Third, mergers and delistings are where the gaps are largest. Dividends and splits can be handled with a single number. Cash acquisitions, stock-for-stock mergers, spin-offs of a new company, and delistings cannot be completed by adjusting a multiplier. The corporate-actions data feed that CF Benchmarks built for xStocks splits events into three classes: cash-flow events publish an “effective scaling factor” and a “cash amount per token”; structural events publish only a scaling factor; and termination events (such as a delisting) publish a settlement price, at which point the token terminates. This is the clearest classification seen so far, but it is a third party’s data product, not a commitment by the issuer. Before listing, you must obtain the issuer’s written procedures for each of these classes of event.
2. Four ways the multiplier is written on-chain
All of them are called “the multiplier,” but the four issuers put it in different places on-chain. Reading it from the wrong place during integration is the most common source of incidents.
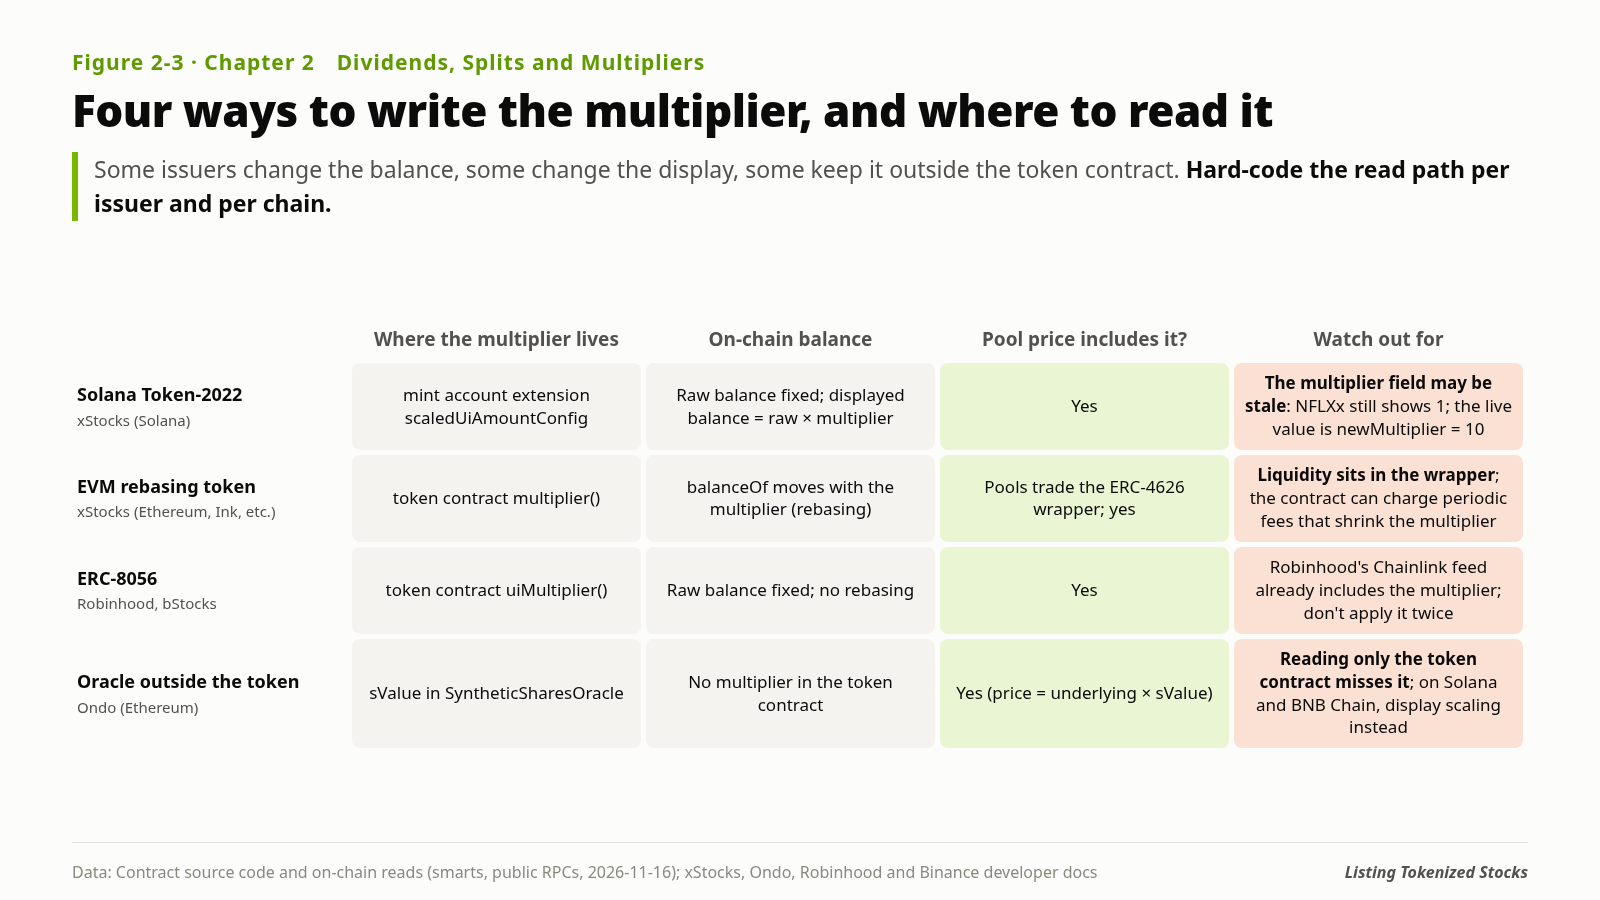
Method 1: the Solana Token-2022 scaledUiAmount extension (xStocks on Solana). The multiplier lives in the extension configuration of the token’s mint account, in three fields: multiplier, newMultiplier and newMultiplierEffectiveTimestamp. The raw amount never changes; the balance a wallet displays = raw balance × current multiplier. We read both fields for TSLAx as 1: it has never paid a dividend, and has not split again since its 2022 split, so this book uses it as the baseline sample for spreads.
Here is the first trap. The “current multiplier” is not the multiplier field: once the current time has passed the effective timestamp, you should use newMultiplier. For SPYx we read multiplier = 1.00573 and newMultiplier = 1.00747, effective 2026-10-31, long past. For NFLXx the multiplier field still reads 1 to this day, and newMultiplier is 10. A system that reads only the multiplier field will treat NFLXx as 1 share and be off by a factor of 10.
Method 2: rebasing tokens on EVM chains (xStocks on Ethereum and other EVM chains). Backed’s contract (BackedAutoFeeTokenImplementation) records “shares” for each address, and balanceOf() returns shares × multiplier; when the multiplier changes, everyone’s balance changes together. That is friendly to wallets and unfriendly to AMM pools: a pool keeps books based on the balance it has recorded, and when the balance is changed from outside, the books no longer reconcile. So on EVM chains xStocks also issues an ERC-4626 wrapped token (called wrapperAddressV2 in the official API, named “Wrapped … xStock”). The number of wrapped tokens does not change; the amount of base token each one can be exchanged for grows with the multiplier. We read convertToAssets(1e18) for the SPY wrapped token on both Ink and HyperEVM as 1.007474, exactly equal to the base token’s multiplier, and also equal to the current multiplier of SPYx on Solana.
The second trap follows from this: on EVM chains, the stablecoin pools hold the wrapped token, not the base token. The author’s multi-underlying monitoring checked each one against xStocks’ official API: there are no stablecoin pools on the base-token addresses. When a platform “integrates xStocks’ SPY,” which contract it integrates, and which one users receive when they withdraw on-chain, must be hard-coded at listing.
This contract has another design feature that is easy to overlook: it supports a management fee deducted automatically each period (feePerPeriod), and the fee is taken by making the multiplier smaller each period. We read feePerPeriod for NVDAx on Ethereum as 0, meaning nothing is currently being deducted. But the switch is in the contract. The multiplier can not only rise because of dividends, it can also fall because of fees, and your monitoring must be able to detect a falling multiplier.
Method 3: ERC-8056’s uiMultiplier() (Robinhood, bStocks). Raw balances and total supply stay unchanged; the token does not rebase. The contract provides conversion functions such as uiMultiplier() (18 decimals, 1e18 = 1.0) and balanceOfUI(), emits a UIMultiplierUpdated event on changes, and allows changes to be scheduled in advance. Robinhood’s developer documentation states explicitly that its tokens “are not rebasing tokens,” that on-chain swaps are unaffected, and that the Chainlink price feed already includes the multiplier in the price. We read Robinhood’s SPY at 1.001718, NVDA at 1.000775 and TSLA at 1; for bStocks, SPYB at 1.001730, NVDAB at 1.000778 and TSLAB at 1.
Method 4: an oracle outside the token contract (Ondo on Ethereum). Ondo’s GMToken contract has no multiplier field at all. We read its source code on Ethereum: it has only minting, burning, pausing and compliance checks. The multiplier, called sValue, lives in a separate contract, SyntheticSharesOracle. The Chainlink price feed for Ondo calculates the token price as “underlying price × sValue.” We read sValue for SPYon at 1.009473, for QQQon at 1.004082 and for TSLAon at 1. Ondo’s documentation also says that on Solana and BNB Chain, wallets that support display scaling will reflect the reinvestment in the displayed balance. In other words, for the same issuer, on Ethereum it is “the price changes,” while on Solana and BNB Chain it is “the displayed balance changes.”
The four methods compress into one sentence: some issuers change the balance, some change the display, and some keep it outside the token contract altogether. Your system cannot assume that “reading the token contract is enough.”
3. “1 token = how many shares”: five traps in what the platform displays
Put these mechanics into your product and the problems converge on one seemingly simple field: how many shares each token represents. Of the five traps below, the first two have already appeared in the data in the previous section.
Trap 1: comparing the per-token price directly with the share price. DEX pools trade raw units, and the price a pool quotes is the price “per raw unit,” which already includes the multiplier. The SPY at the start of the chapter is the example: on Solana, SPYx was quoted 0.77% above the underlying, but only 0.02% above after dividing by 1.007474. For any spread monitoring and any “premium” alert, step one is dividing by the current multiplier.
Trap 2: reading a stale multiplier field. Solana’s multiplier and newMultiplier, and the Backed contract’s lastMultiplier and multiplier(), all follow an “old value + new value + effective time” structure. Read the storage field directly without checking the effective time, and NFLXx is off by a factor of 10 and SPYx by 0.17%. The correct approach is to call the “current value” function the contract provides, or to apply the effective time yourself.
Trap 3: balance and price in two different units. If you show users a balance already multiplied by the multiplier (the displayed balance), while the price is the pool’s per-raw-unit price, the position’s market value is inflated by the multiplier a second time: by 0.75% for SPYx and by a factor of 10 for NFLXx. Conversely, if the balance is in raw units and the price is the underlying share price, market value is understated. There is only one rule: either use raw units for both, or convert both to shares.
Trap 4: the oracle has already applied it, and you apply it again. Robinhood’s documentation says the Chainlink price feed “automatically includes the multiplier in the price”; Ondo’s Chainlink price feed is “underlying price × sValue.” If your lending protocol takes such a token price feed and then multiplies it by the displayed balance, collateral is overvalued by one multiplier. Conversely, if you take the underlying share price feed and multiply by the raw balance, collateral is undervalued: by 0.75% for SPYx, and by 0.95% for Ondo’s SPYon. Undervaluing is a conservative mistake; overvaluing lets people borrow money they should not be able to borrow. Chapter 7 uses this point when discussing collateral.
Trap 5: multipliers for the same stock from different issuers are not interchangeable. The SPY multipliers read on the same day: Robinhood 1.001718, bStocks 1.001730, xStocks 1.007474, Ondo 1.009473. The differences come from the issuers’ different launch dates (and therefore the number of ex-dividend dates each has been through), and possibly also from differences in withholding-tax basis and reinvestment execution prices. None of the issuers has published how the difference breaks down [To verify: each issuer’s history of SPY multiplier changes and the corresponding dividends]. The same issuer is consistent across chains: xStocks’ NVDA reads 1.001701 on Solana, Ethereum, Ink and HyperEVM alike. But treat that only as a validation result: multipliers must be maintained and read individually by issuer, underlying, chain and contract version, and never maintained centrally by ticker. The conversion convention used throughout this book is fixed: token unit price ÷ multiplier = price per share; underlying share price × multiplier = reference price per token unit.
4. What kind of fake spread an uncorrected multiplier creates
What follows is a worked example using a fictional dividend-paying stock. All numbers are illustrative, purely to show the mechanism.
Suppose a stock closes at $100 the day before its ex-dividend date and pays a dividend of $1 per share, with 30% withholding tax. One issuer’s token has never been through a dividend since launch, and its multiplier is 1.000.
- Ex-dividend date, at the open. As usual, the stock goes ex the $1 and opens around $99. The holder is entitled to a dividend of $0.70 per share (after tax), which the issuer will use to buy 0.70 ÷ 99 ≈ 0.00707 more shares, raising the multiplier from 1.000 to about 1.00707.
- Ex-dividend date, intraday, before the multiplier is updated. Taking xStocks as an example, the new multiplier activates only at 00:30 UTC the day after the ex-dividend date. Throughout that day, token holders’ right to the $0.70 is perfectly real; it just isn’t reflected in the multiplier yet. So the fair price per raw unit of the token is about 99 × 1.00707 ≈ $99.70. If the system computes the reference price as “underlying price × current multiplier of 1.000,” it will see the token at a “0.7% premium.”
- After the multiplier is updated. The multiplier becomes 1.00707, the reference price becomes 99 × 1.00707 = $99.70, and the “premium” disappears.
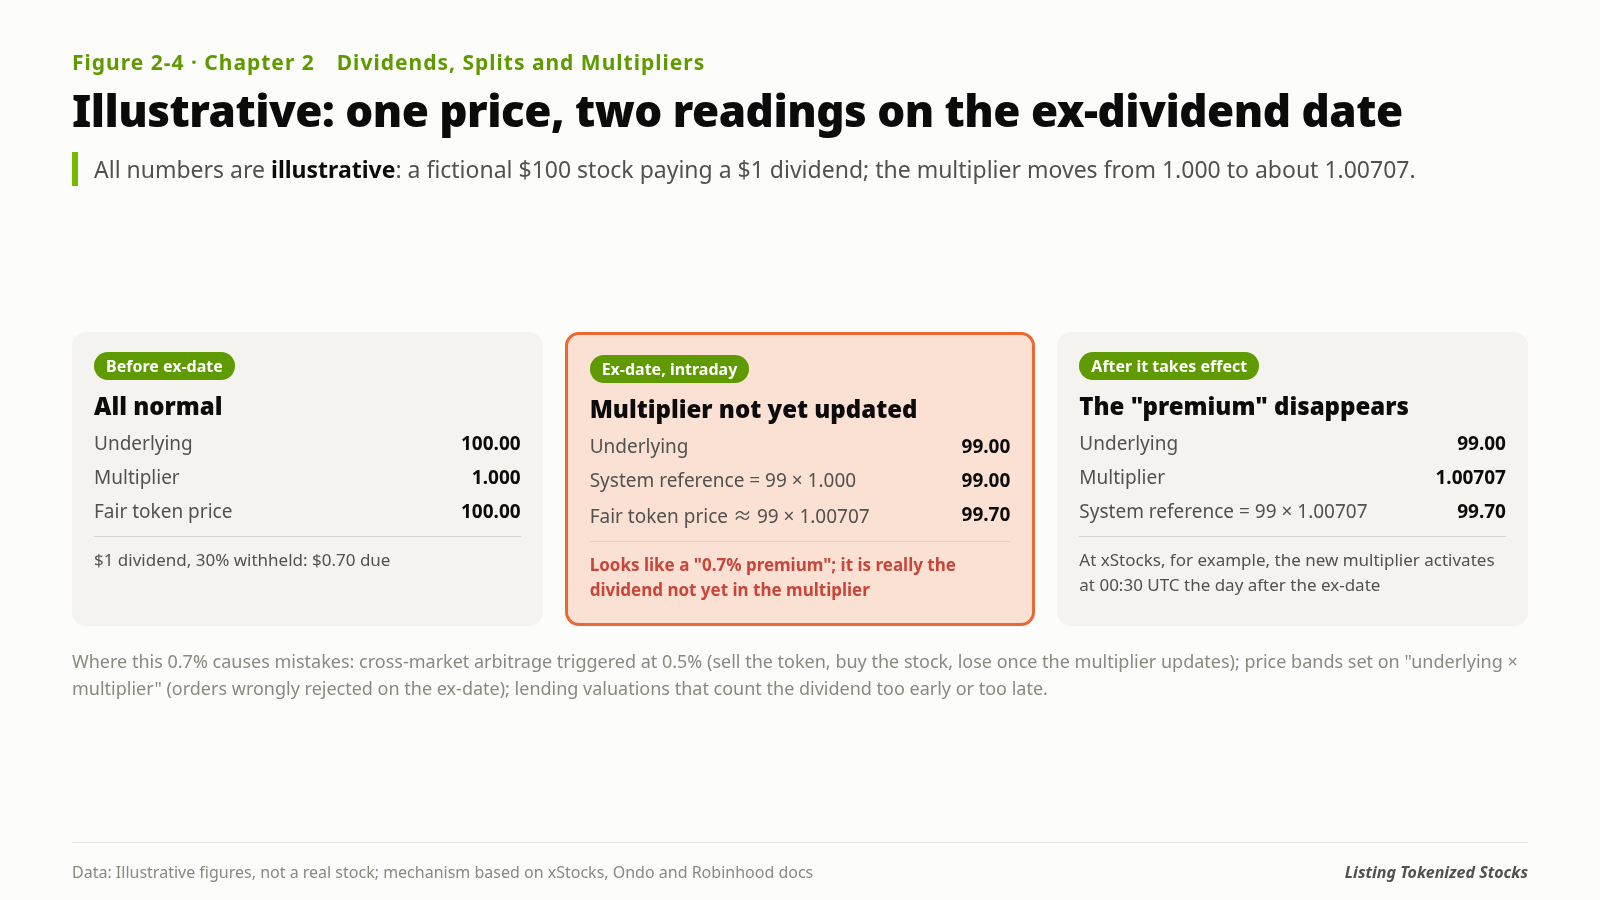
This 0.7% fake spread causes real money to be lost in three places:
- Market making and arbitrage. A cross-market strategy triggered at a 0.5% threshold will sell the token and buy the underlying on the ex-dividend date; once the multiplier updates and the spread disappears, it loses its fees and hedging costs.
- Price bands. If your matching engine uses “underlying price × multiplier” as a price band and rejects orders deviating by more than 0.5%, it will reject a large number of normal orders on the ex-dividend date.
- Lending liquidations. The error in the opposite direction exists too: if you use the token price feed but bring forward the switch to “underlying price × new multiplier” on the ex-dividend date, you count a dividend that has not yet arrived as collateral.
The real-world order of magnitude can be calibrated against the SPY at the start of the chapter: xStocks’ cumulative SPY multiplier is 1.0075 and Ondo’s is 1.0095, each the result of more than a year of dividends stacked up. A single ex-dividend jump for SPY is 0.2%–0.3%; for a stock with a 4% dividend yield, one quarter comes close to 0.7%.
5. Your options
Option A: convert everything to shares inside the system. For each token, store three quantities: raw balance, current multiplier and the multiplier’s effective time; express all prices and balances externally in “shares.” The benefit is direct comparability with the underlying stock and with other issuers. The cost is that the multiplier must be updated on time at every corporate action, and any missed update will misalign prices.
Option B: use raw units everywhere inside the system and convert only for display. The price is the pool price, the balance is the on-chain balance, and the multiplier appears only in the display layer. The benefit is a one-to-one match with the on-chain ledger and simple reconciliation. The cost is that cross-issuer comparison, spread monitoring and risk thresholds all need separate conversion, which someone is liable to forget.
Option C: rely entirely on “multiplier-included” prices from the issuer or the oracle. It saves effort, but you hand the correctness of the multiplier entirely to a third party, and you have to confirm whether it is actually included (Robinhood’s and Ondo’s Chainlink price feeds include it; underlying share price feeds do not).
Whichever you choose, three things are mandatory:
- Hard-code the multiplier read path per issuer and per chain, never shared by ticker;
- Alert separately on multiplier changes, both increases and decreases, and stop quoting if the size of a change does not match the announcement;
- Set a pause window around the effective time. xStocks’ developer documentation recommends that trading venues pause interaction with the token for about 15 minutes on each side of every multiplier activation. It also says multipliers are published on-chain in advance and that integrators should switch locally when the effective time arrives; the push notifications it mentions are not yet live. Ondo, bStocks and Robinhood also pause some functions during corporate actions.
Ten questions to ask the issuer (or yourself) before listing
- Where on-chain is the multiplier? Is it a field in the token contract, a token extension, a separate oracle, or published only off-chain? Which function should be called to read the “current value”?
- On each chain, have you deployed the base token or a wrapped token? Which one has the secondary-market liquidity? Which one do users receive when they withdraw on-chain?
- Can the multiplier fall because of fees? Is there an automatic fee-deduction switch in the contract, and what is it set to now?
- At what rate is withholding tax applied to cash dividends? Are holders’ tax-treaty countries distinguished? Which document says so?
- How far in advance is each multiplier update announced? How is the effective time set (ex-dividend date, record date, payment date)? Is there a notification or event to subscribe to?
- How long is the processing window for splits and reverse splits? Which functions are paused within the window (trading, transfers, creation/redemption, deposits and withdrawals)?
- How are cash acquisitions, stock-for-stock mergers, spin-offs and delistings each handled? With stablecoins, with new tokens, or by terminating at a settlement price? How is the settlement price determined?
- For a corporate action that offers “cash or stock” as an election, who makes the choice on behalf of holders?
- What happens if a multiplier is miscalculated? Is there a correction mechanism, and has a correction ever been made?
- (Ask yourself) For our displayed balances, prices, collateral valuation and reconciliation, which use raw units and which use shares? Is there any place where the multiplier is applied twice, or not at all?
Conclusion
The multiplier is the least conspicuous number on a tokenized stock, and the easiest to get wrong. It determines how many shares “1 token” really is: on the same day, for the same SPY, four issuers gave four answers.
Divide by the multiplier before you talk about spreads; confirm where to read the multiplier before you talk about integration.
Sources for this chapter
On-chain readings (taken directly by the author, 2026-11-16 17:50–18:10 UTC):
- xStocks / Solana:
scaledUiAmountConfigof each mint account (Solana mainnet public RPCgetAccountInfo, jsonParsed). TSLAx (Xs…zoB) multiplier = newMultiplier = 1; SPYx (XsoC…F2W) multiplier 1.0057322, newMultiplier 1.0074741, effective 2026-10-31 13:45 UTC; AAPLx 1.0038023 (effective 2026-11-12); NVDAx 1.0017012 (effective 2026-09-10 00:30 UTC); MSFTx 1.0059034 (effective 2026-08-20 00:30 UTC); NFLXx (XsEH…VpL) multiplier 1, newMultiplier 10, effective 2025-11-16 23:55 UTC. - xStocks / Ethereum: NVDAx 0xc845…849d, contract
BackedAutoFeeTokenImplementation(verified source via smarts),multiplier()= 1.0017012,multiplierNonce= 5,feePerPeriod= 0. - xStocks / Ink and HyperEVM wrapped tokens (ERC-4626): wTSLAx 0xc3Fd…1171
convertToAssets(1e18)= 1.0; SPY wrapper 0xe7e5…b540 = 1.0074741; NVDA 0xa8dd…50d5 = 1.0017012; QQQ 0x4c1a…01f7 = 1.0034561; each equal to its base token’smultiplier(). - Robinhood Chain:
uiMultiplier()(smarts) SPY 0x117c…4c0c = 1.001718; TSLA 0x322F…3b2d = 1.0; NVDA 1.000775 (multipliercolumn of the author’s multi-underlying monitoring, sourced from api.robinhood.com/rhj/assets). - bStocks / BNB Chain: contract
SecuritiesToken+ ERC-8056 (source via smarts);uiMultiplier()SPYB 0x7138…82D8 = 1.0017298, NVDAB 0x02Fc…7436 = 1.0007782, AAPLB 1.0011354, MSFTB 1.0013140, TSLAB 0x5b19…292f = 1.0. - Ondo / Ethereum: GMToken (TSLAon 0xf6b1…103f, verified source via smarts, no multiplier field); SyntheticSharesOracle 0x9BC3…41bE6
getSValue(): SPYon 1.0094731, QQQon 1.0040824, TSLAon 1.0. - Prices: author’s multi-underlying monitoring
stocks_spread.csv, 2026-11-16 17:57 UTC (DexScreener; methodology in Chapter 4); NFLXx price (DexScreener) and NFLX share price and split record (Yahoo Finance, 10:1, 2025-11-17).
Issuer and third-party documentation (consulted 2026-11-16):
- xStocks Docs, “How xStocks Handles Dividends & Stock Splits” https://docs.xstocks.fi/developers/multipliers : implementation on each chain, activation time (00:30 UTC the day after the ex-dividend date), recommended pause of about 15 minutes, push notifications not yet live
- xStocks Partner Hub, “Learn” and “Corporate Actions” https://xstocks.fi/partners/learn
- CF Benchmarks, “xStocks Product Suite is Live”: three classes of events in the corporate-actions data feed
- Ondo Docs, “Corporate Actions” https://docs.ondo.finance/ondo-stocks/corporate-actions ; Chainlink Docs, “Ondo Finance Global Markets (GM)” https://docs.chain.link/data-feeds/tokenized-equity-feeds/ondo : Token Price = underlying price × sValue; pause mechanism for splits
- Binance, “Frequently Asked Questions on bStocks” and the bStocks landing page: multiplier, pauses during ex-dividend and split processing, treatment of corporate actions
- Robinhood Chain Docs, “Stock Tokens” and “Building with Stock Tokens” https://docs.robinhood.com/chain/stock-tokens ; RHJ, “Corporate Actions” https://docs.robinhood.com/rhj/corporate-actions
- Where Does the Yield Come From, Chapter 6: multiplier increments for five Robinhood tokens ≈ dividend yield × 0.69
- BTech Holdings (bStocks) prospectus: dividends reinvested after deduction of 30% US withholding tax, multiplier pass-through (first-hand excerpts stored in
review/sources/dl/bt/)
[To verify]
- Each issuer’s history of SPY multiplier changes and the corresponding dividends: needed to break down the sources of the difference between 1.0017 / 1.0075 / 1.0095 (launch date, withholding tax, reinvestment price); this chapter did not trace them change by change.
- When bStocks dividends take effect: the website landing page says “reinvested on the ex-dividend date,” the FAQ says “multiplier updated shortly after the record date”; confirm with the issuer which applies.
- Each of the four issuers’ specific terms for cash acquisitions, stock-for-stock mergers, spin-offs and delistings: not in public documentation; check each prospectus or ask the issuer.
- sValue for Ondo tokens other than SPYon, QQQon and TSLAon: calls to
getSValue()for addresses such as NVDAon revert (possibly using a different oracle contract); this chapter did not pursue it further.